Discover how Fort Myers new construction loans are evaluated for investment property projects in Southwest Florida. Unpack lender expectations, builder requirements, and what matters most for approval.
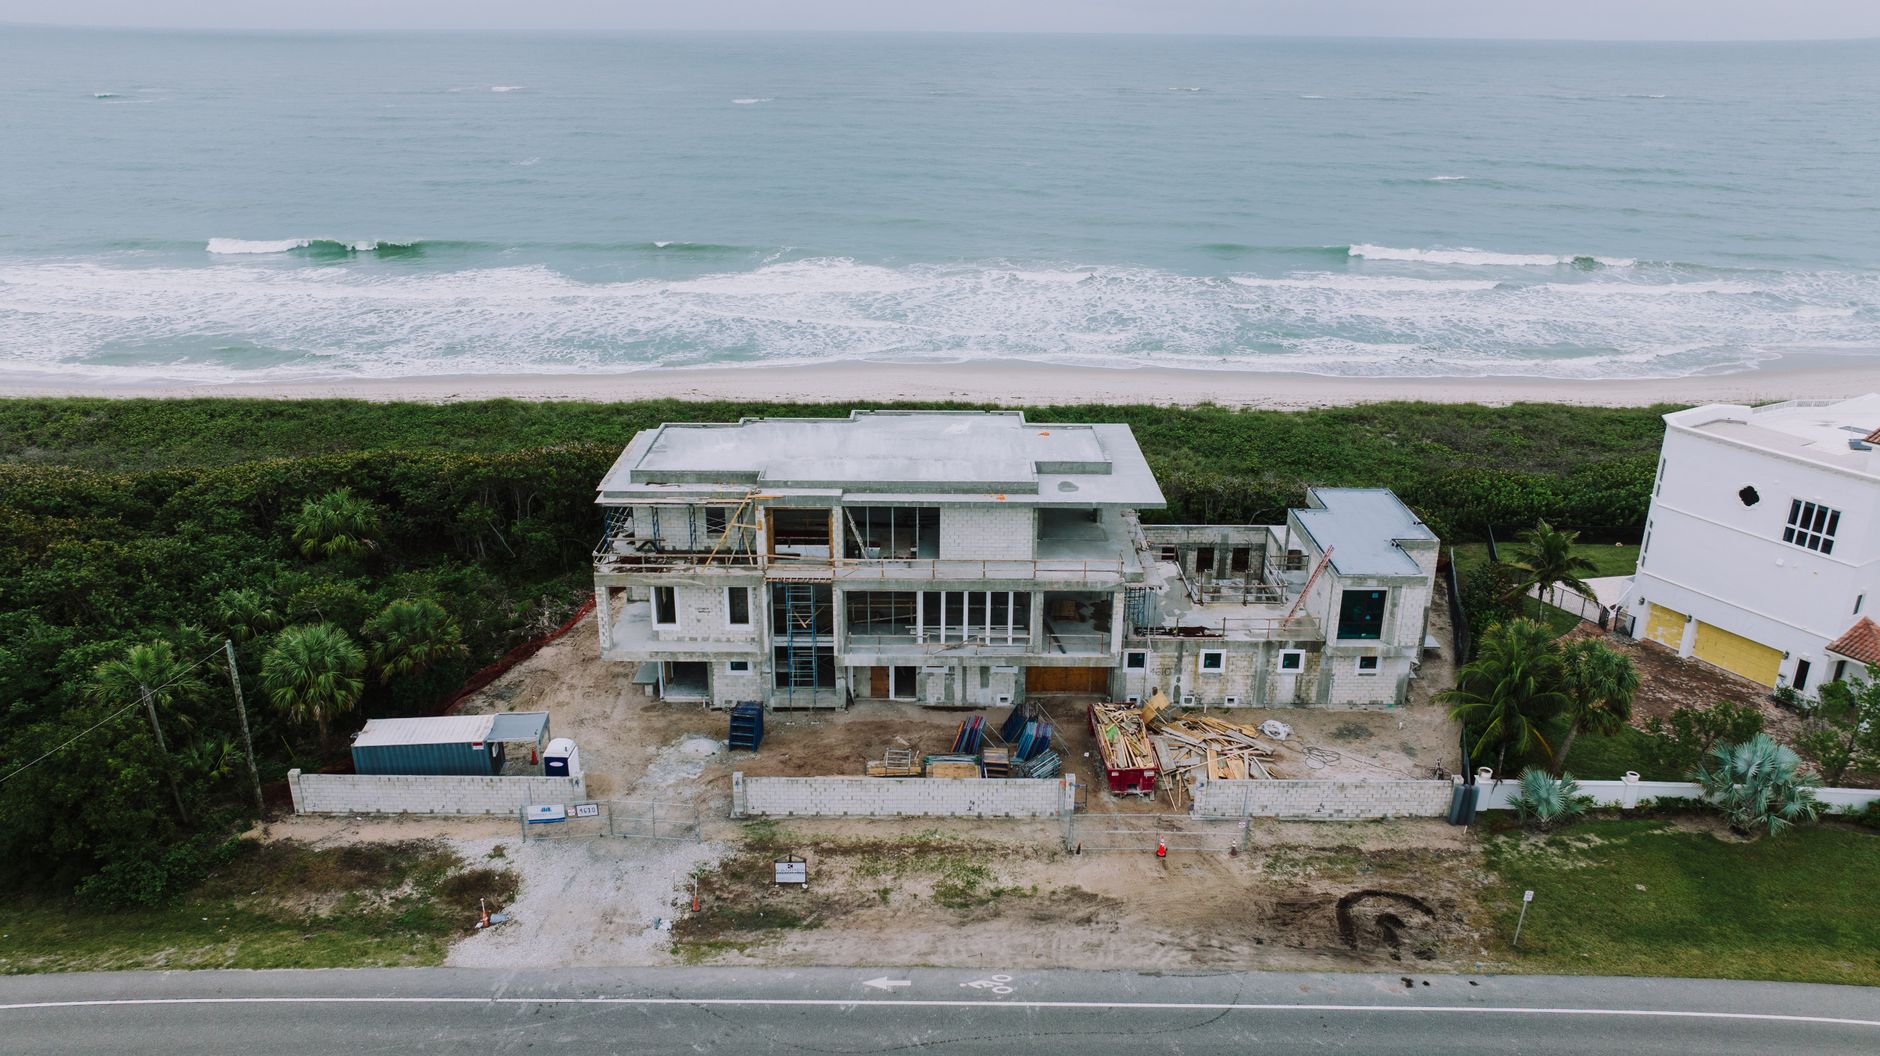
For builders and real estate investors focused on Southwest Florida, understanding how to qualify for Fort Myers new construction loans can be the key to unlocking the full potential of your next ground-up, rehab, or rental project. Whether you're active in Cape Coral, Lehigh Acres, Estero, or beyond, the right investor financing can make or break execution as land, labor, and insurance challenges intensify across Lee County.
This investor-focused guide unpacks what makes a new construction deal financeable in Fort Myers, which variables carry the most weight in underwriting, and the practical realities when dealing with private lenders such as AFI Private Lenders. If you’re seeking private financing for a commercial or residential investment property, these are the key steps, checks, and trade-offs you’ll face in today's market.
What Makes a Ground-Up Construction Request Financeable?
When evaluating Fort Myers new construction loans, private lenders look beyond the land alone. A financeable request often begins with a clear investment thesis—such as building and holding rentals in North Fort Myers, executing a value-add in Lehigh Acres, or infilling a Cape Coral site for resale. Lenders prioritize the project's feasibility, strength of plans, and whether the team can realistically complete construction within the proposed budget and timeline.
AFI Private Lenders considers the structure of each deal, weighing project readiness and risk. Viable deals usually have clearly defined scope, a workable budget, committed team members, and a well-articulated exit. Projects that are speculative, undercapitalized, or lacking local insight often require a different financing structure—or may not fit at all.
Land, Plans, Permits and Project Readiness
Securing or controlling the right parcel is just the starting point. Whether it's infill in Fort Myers proper or undeveloped acreage on the outskirts, lenders examine if the exact parcel is suitable for the proposed use and if entitlements line up. Investors need to present a site plan, building plans, and documentation that permitting is underway or complete. Lee County and municipal review processes can impact timelines; readiness with plans and permits is a signal of execution capability.
In markets like Estero or Bonita Springs, where permitting departments may vary in speed and requirements, investors benefit from presenting clear evidence of documentation progress. Lenders are more likely to move forward when a project is shovel-ready—or close—with permit risks well understood.
Builder, General Contractor and Project-Team Considerations
The experience, licensing, and local-market track record of your builder and general contractor matter tremendously. AFI Private Lenders will review the chosen professionals' ability to execute the planned scope of work, manage subs, navigate code and insurance requirements, and deliver the finished product on time.
First-time builders may be considered, but approval depends heavily on surrounding team strength, construction support, and demonstration of readiness for Southwest Florida's unique construction challenges—such as weather delays or storm-related requirements.
Budget Detail, Contingency and Borrower Liquidity
Lenders expect a granular, line-item budget covering hard and soft costs, insurance, permits, and municipal fees relevant to Fort Myers or any Lee County community. Underestimating true costs is a common reason projects derail. A built-in contingency reserve is essential, as unexpected price increases or delays can jeopardize timelines. Borrower liquidity is also reviewed to confirm you can cover down payments, reserves or cost overruns should they arise.
Strong borrower financials—and a practical approach to budgeting—add confidence that you’ll weather the inevitable hiccups that come with new construction in Southwest Florida.
How Construction Draws Work After Closing
With Fort Myers investment property loans, funds are typically disbursed through construction draws—each triggered by evidence of completed work or key milestones. AFI Private Lenders aims to keep the process straightforward and practical for qualifying projects, with draws subject to inspection, documentation, and the loan agreement. This means you’ll need to manage progress reporting and draw requests with care, as funds release only follows confirmed progress and satisfactory inspections.
Effective draw management is essential to keeping work moving and contractors paid, especially for larger or multi-phase projects in communities like Lehigh Acres or Estero.
Schedule Risk, Cost Overruns and Change Orders
Lee County's construction environment presents real risks: storm-related delays, labor shortages, and unpredictable price swings can all disrupt schedules. Each change order—whether due to unforeseen site issues or a material upgrade—adds time as well as cost. Lenders will scrutinize how you plan for and manage these variables.
Experienced teams present a buffer for contingency, demonstrate familiarity with permitting jurisdictions, and proactively communicate with their lender as changes arise. When risk factors are high or uncertainty is present, alternative or staged financing might be more prudent.
Sale, Refinance and Rental-Stabilization Exits
Every Fort Myers new construction loan must have a clear exit strategy. Common exits include selling to an end user or investor once construction is complete, refinancing into long-term investor-grade mortgages, or holding for rental stabilization. Each option carries distinct insurance, timeline, and lender review requirements.
Rental investors in markets like Cape Coral or Bonita Springs should be prepared to demonstrate local property management experience or partnerships and realistic pro-forma rents. For sale or refinance, a demonstrable pipeline of buyers or lenders—and supportive market trends—bolster lender confidence.
A Construction-Loan Submission Checklist
- Purchase contract or deed for land
- Final plans, specs, and site plan
- Evidence of permitting status
- Detailed, line-item construction budget with contingency
- Proof of builder/license and team credentials
- List of key subs and vendors (as known)
- Insurance quotes or commitments
- Borrower financials and liquidity statements
- Exit strategy—sale, refinance, or rental plan
Submitting a comprehensive package up front helps the lender underwrite your deal more efficiently—and identifies gaps that could stall funding or construction once underway.
Real Estate Investor Financing FAQs
What types of new construction projects in Fort Myers are considered for private investment loans?
AFI Private Lenders reviews ground-up, rehab-to-new, and infill development projects for business purposes, including single-family, duplex, and small multifamily investment properties.
Does property location within Lee County impact new construction loan terms?
While AFI Private Lenders serves Fort Myers and nearby communities like Cape Coral or Bonita Springs, each project is evaluated individually based on local risks, team, and project strength—not simply on location.
How important is builder or contractor experience for qualifying?
Builder and GC experience is a key underwriting factor. First-time builders may be considered if they have strong teams and project plans, but established track records improve approval odds.
How are construction loan draws managed after closing?
Draws are typically made upon confirmed completion of project milestones, subject to inspection and documentation. Proper management and timely reporting keep funds flowing.
Can I use Fort Myers new construction loans for a rental investment strategy?
Yes, qualifying projects can be structured for sale, refinance, or rental stabilization exits. Lenders will review your planned exit, pro-forma rents, and management capacity.
Are there minimum credit score requirements?
Traditional credit scoring is not the main qualifying factor. Project strength, builder experience, budgeting, and exit strategy are given more weight for fix-and-flip and investment projects.
What should I prepare before applying for a property construction loan?
Gather your land purchase documents, finalized plans, permit updates, detailed budgets, builder credentials, insurance quotes, proof of funds, and a clear exit strategy.
Have a Fort Myers investment property to finance?
Send the property address, requested loan amount, property type and investment plan for an initial review.