
A practical guide to securing new construction loans in Palm Beach County, with an emphasis on project readiness, budgeting, draw planning, and exit strategy.
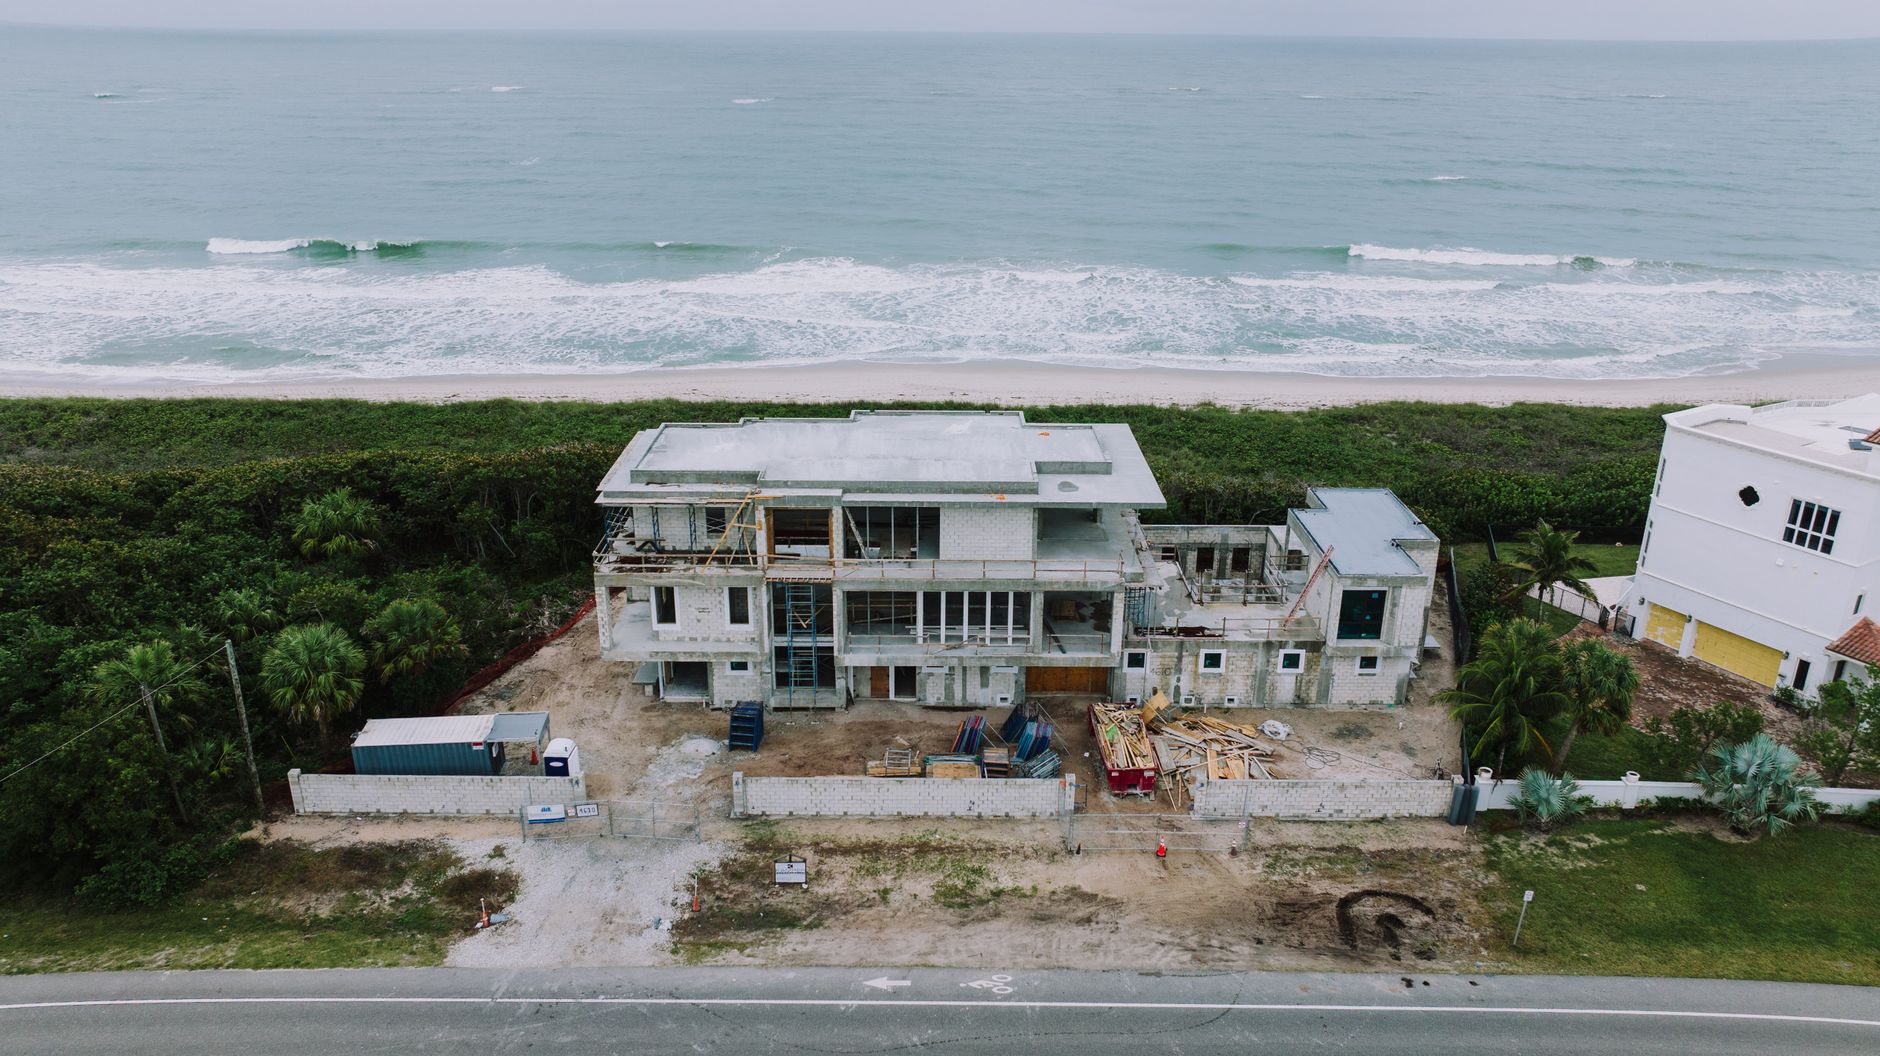
Investors and builders in Palm Beach County seeking to construct homes, townhomes or multifamily properties know that assembling the right capital stack is only one part of a successful project. New construction loans in Palm Beach County require proof of planning, skilled team members, budget controls, and a realistic exit—a focus that is even more crucial in South Florida’s competitive property markets.
This guide breaks down how private construction lenders approach project reviews and approvals in West Palm Beach, Boca Raton, Delray Beach and other communities, so you can make confident decisions and set up your ground-up development to succeed from day one.
What Makes a Ground-Up Construction Request Financeable?
Not every site or project is immediately financeable with private construction lenders in Palm Beach County. Lenders look for more than just a desirable location: they weigh land control, zoning potential, clear project plans, and whether your business purpose aligns with their risk profile. Beyond standard "leverage" targets, lenders evaluate your team’s experience, your understanding of construction costs, and your exit strategy. Speculative builds, infill projects, and new construction in growth areas like Jupiter or Lake Worth Beach are considered only if site control and feasibility are clearly demonstrated. A financeable ground-up request starts with a complete, verifiable project vision and risk mitigations.
Land, Plans, Permits and Project Readiness in Palm Beach County
Lenders typically want to see that you own or have a binding contract for the land, that your architectural plans match the site’s buildable footprint, and that you understand local permitting paths—though each municipality from Wellington to Palm Beach Gardens may have unique requirements. Most private lenders will not require permits to be fully issued before reviewing your construction request, but projects still in conceptual stages face higher scrutiny. Early coordination with licensed professionals and city or county officials helps accelerate readiness, reduce risk, and strengthen your loan application. Always verify local zoning, title, and code restrictions prior to submitting.
Builder, General Contractor and Project-Team Considerations
Even seasoned investors benefit from assembling a capable, licensed builder or general contractor with recent ground-up experience in Palm Beach County communities like Delray Beach or Royal Palm Beach. Lenders are more receptive to requests where all major team members—GC, architect, subs, and engineers—are identified up front. While AFI Private Lenders may consider first-time builders, having a strong supporting team and clear project roles can make a significant difference in underwriting. Vet your team’s insurance and licensing status for the construction type prior to applying.
Budget Detail, Contingency and Borrower Liquidity
One of the most common reasons ground up construction loans in Palm Beach County fall short is an incomplete or overly optimistic budget. Lenders will request line-item construction budgets, labor breakdowns, and credible cost sources. A realistic contingency reserve—typically a percentage built in for cost overruns—shows you understand construction risk. Private lenders also weigh your liquidity: the ability to cover unforeseen costs, interest, and ongoing project expenses. These factors affect not only approval odds, but also loan structure and draw schedules. Budget clarity is especially critical for spec home financing and for managing projects close to the Intracoastal or in flood-prone areas, where costs and risks may rise.
How Construction Draws Work After Closing
Construction draws are incremental disbursements of funds as work progresses. In Palm Beach County, lenders such as AFI aim to keep draw requests straightforward and practical—typically based on work completed, subject to inspections and documentation. Most require you to complete scheduled milestones before approving the next draw, which protects both lender and borrower from loss. Advanced preparation with your contractor’s projected draw schedule and submitting timely inspection or progress reports can smooth the process. Validating that your budget matches your draw schedule and includes room for delays is crucial for both builder and lender success.
Schedule Risk, Cost Overruns and Change Orders
Unexpected delays—caused by weather, permitting holdups, supply chain shortages, or subcontractor issues—are common in South Florida construction. Schedule risk can threaten project profitability and exit timing across markets like Boynton Beach or Loxahatchee. Private lenders closely analyze your timeline for realism and logic. Cost overruns, whether from underestimated labor or material costs or post-approval change orders, impact both your bottom line and loan covenants. Building in a realistic buffer for both time and money, and proactively communicating with your lender about any scope changes, can preserve your project's viability.
Sale, Refinance and Rental-Stabilization Exits
Your exit strategy is a core element evaluated by private construction lenders. Whether your goal is to sell the finished property in Palm Beach, refinance into permanent debt, or stabilize as a rental, showing credible paths to repayment is essential. Each exit option has trade-offs: spec home sales are market dependent, rental exits require clean lease-up and solid rent assumptions, and refinance options depend on post-construction appraisals and property performance. Be prepared to support your plan with data, realistic timelines, and market contacts, especially in dynamic areas like West Palm Beach or Boca Raton. Lenders want to know you have contingency plans if sales or refinancing takes longer than expected.
A Construction-Loan Submission Checklist
Before you submit any request for new construction financing in Palm Beach County, ensure your package includes the following:
- Proof of land control (ownership or binding contract)
- Architectural plans, surveys and site studies
- Detailed, line-item construction budget with contingency
- Resumes and licenses for builder/GC and key team members
- Permitting and zoning status summary (check with the city or county)
- Projected construction timeline and scheduled draw requests
- Proof of liquidity or available reserves
- Clear exit strategy: sale, refinance, or rental stabilization plan
Reviewing these items before reaching out to private construction lenders in Palm Beach County can help your request stand out and speed up the due diligence process.
Real Estate Investor Financing FAQs
What types of projects qualify for new construction loans in Palm Beach County?
Projects like spec homes, townhomes, infill developments and multifamily properties may qualify, provided land, plans, budget, team, and exit strategy are strong.
Can first-time builders get private construction financing?
First-time builders can be considered if they have a credible team, thorough plans, a realistic budget, and a clear exit, but approval is not guaranteed.
Do I need permits in hand before applying for a loan?
You generally do not need fully issued permits to apply, but demonstrating that permits are attainable and your plans are realistic is essential.
How does the construction draw process work?
After closing, funds are released in stages based on work completed. Draws require inspections and documentation per the lender's requirements.
What is the typical contingency reserve for construction loans?
Contingency reserves vary, but lenders expect a budget line for unforeseen costs to mitigate risk. The specific percentage depends on project complexity.
How do private lenders evaluate exit strategy for construction financing?
Lenders expect realistic exit plans, such as sale, refinance, or rental stabilization, with supporting data and a backup strategy if timelines shift.
Have a Palm Beach County investment property to finance?
Send the property address, requested loan amount, property type and investment plan for an initial review.