A practical guide to securing Lakeland new construction loans for investment properties, centered on project feasibility, investor readiness, and disciplined exit planning.
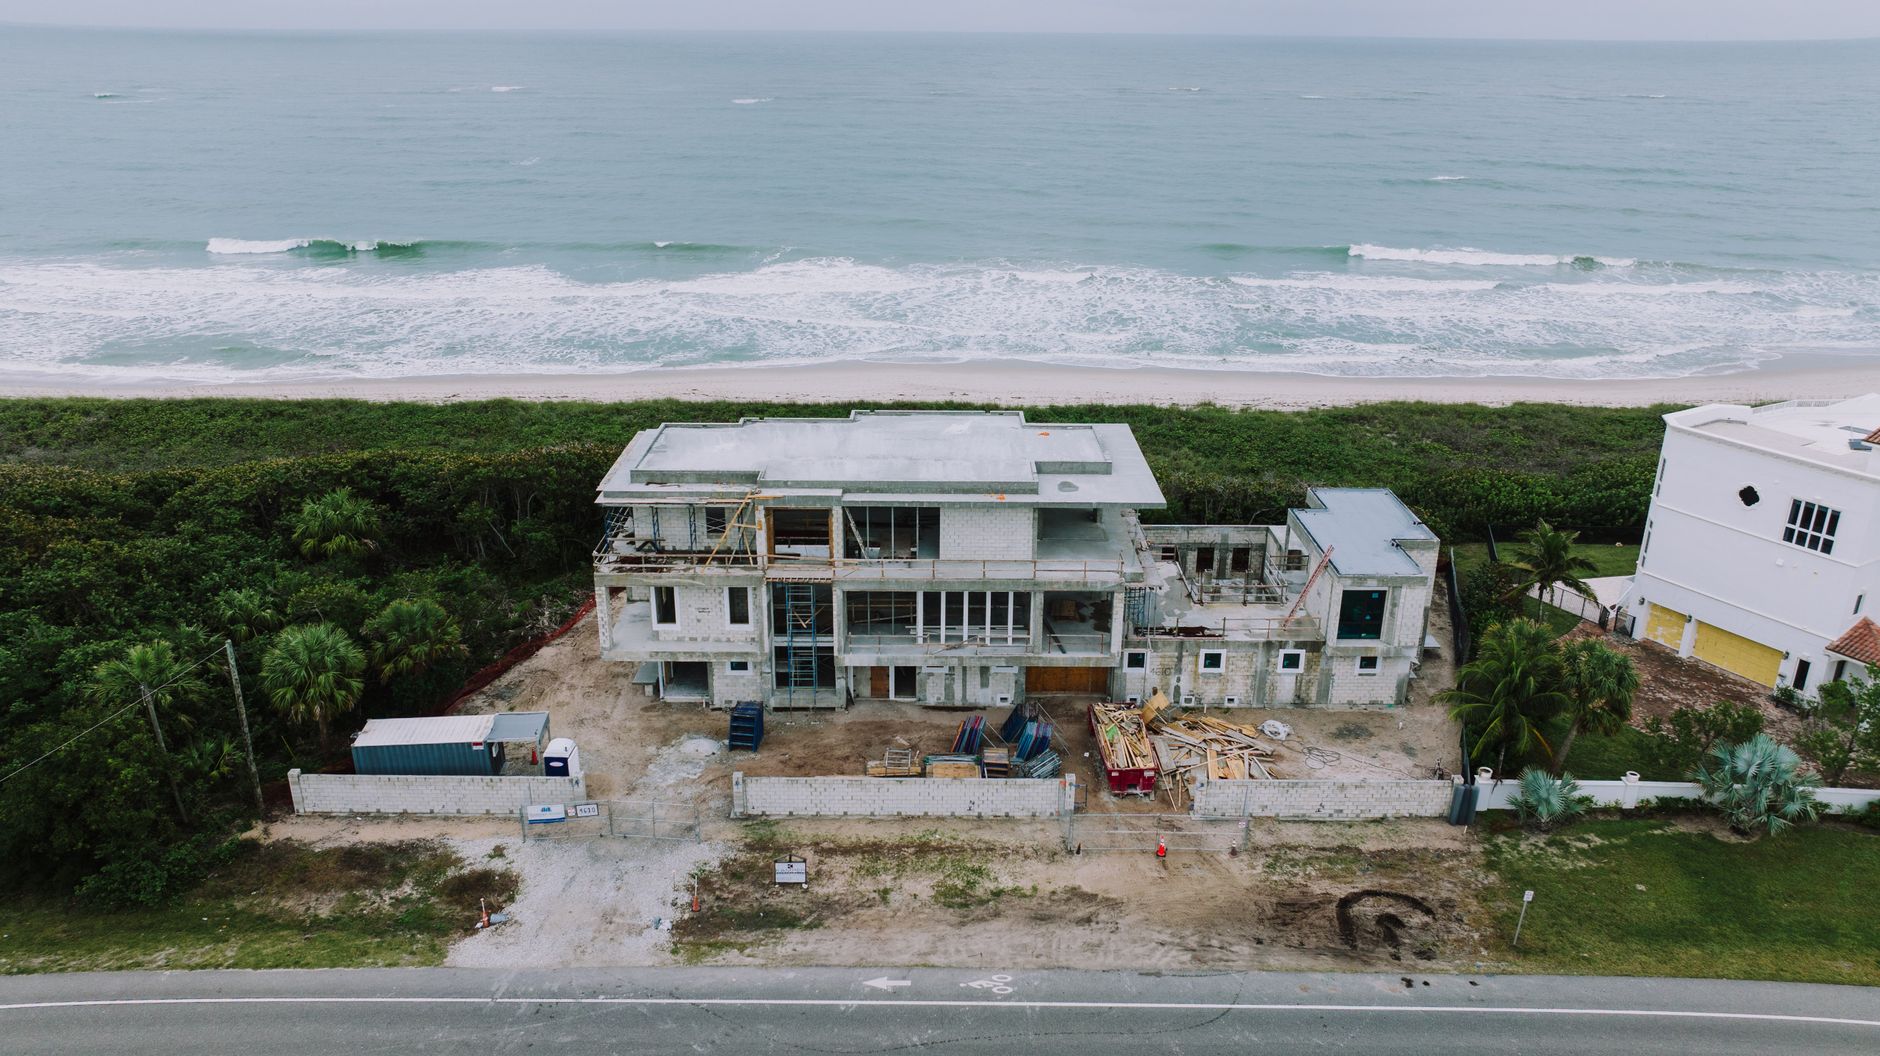
New construction loans in Lakeland, Florida, are a valuable tool for real estate investors eyeing Central Florida’s inland opportunities. From Winter Haven to Bartow, Polk County’s growth corridor attracts those who prioritize disciplined budgeting and smart exit strategies for investment property projects.
This guide explains how Lakeland new construction loans are evaluated and what makes financing requests more appealing to private lenders, including AFI Private Lenders. Each step—land readiness, team experience, financial controls, and draw management—plays a distinct role in a project’s financeability.
What Makes a Ground-Up Construction Request Financeable in Lakeland
Lenders specializing in Lakeland new construction loans, such as AFI Private Lenders, look beyond just property value. In inland markets like Lakeland and Winter Haven, financeable requests highlight a clear investment purpose, realistic scope, and practical plans. Lenders typically seek evidence that the project addresses local demand, can be completed within the investor’s budget, and has a defined exit. Requests are strengthened by precise information, transparent financials, and a team capable of navigating Central Florida’s construction environment.
Land, Plans, Permits and Project Readiness
A solid Lakeland new construction loan application begins with land that’s either owned or under contract, with clear access and utility feasibility. Lenders want to see site control, engineered plans, permitting steps underway, and a timeline that realistically reflects Polk County’s process. For investment properties in Bartow or Auburndale, being able to provide surveys, environmental information, and permit histories makes the request stronger. The more prepared your project is, the more confident a lender can be about draw approval pace and timeline adherence.
Builder, General Contractor and Project-Team Considerations
In Lakeland and neighboring cities, lender confidence increases when the construction team’s experience aligns with the project’s size and complexity. While AFI Private Lenders may review requests from first-time builders, established contractors and verifiable track records help reassure lenders that unforeseen local challenges—such as weather or subcontractor availability—will be managed. Investors should be ready to present resumes, references, and contractor agreements when seeking new construction loans in Lakeland, Florida.
Budget Detail, Contingency and Borrower Liquidity
Lakeland investment property loans favor borrowers who demonstrate a disciplined, detailed budget with built-in contingency reserves. Lenders typically look for line-item budgets that show both hard and soft costs, along with realistic estimates for unexpected expenses. Your liquidity—the cash you can deploy if needed—signals your ability to absorb delays or overruns during construction. In a market where price volatility is possible, well-prepared budgets and clear evidence of reserves set requests apart.
How Construction Draws Work After Closing
Lenders like AFI aim to make construction draw requests practical for qualifying Polk County projects. After closing, draws are typically released based on completed work, verified by inspection and documentation per the loan agreement. In Lakeland, ensuring that all permits are secured and work is completed to code is essential for timely draws. Strong communication with both lender and contractor streamlines draw approvals and reduces funding gaps mid-project.
Schedule Risk, Cost Overruns and Change Orders
Lakeland’s construction environment requires proactive planning for unexpected events, such as weather delays or material shortages common throughout Central Florida. Private lenders expect borrowers to address schedule risks and outline processes for handling change orders. Clear documentation and transparency allow for smoother lender reviews and protect the project’s budget as unplanned changes arise. Contingency planning—financial and operational—is a must for local investors.
Sale, Refinance and Rental-Stabilization Exits
Polk County real estate investor financing favors those with defined, realistic exit strategies. Whether you plan to sell new homes, refinance into long-term debt, or hold stabilized rentals, lenders evaluate the plausibility of your exit, market demand, and personal experience. Lakeland and Plant City investors should present supporting data for the chosen exit path, such as sales comps or rental projections. Exit discipline not only appeals to lenders but also mitigates your own investment risk.
A Construction-Loan Submission Checklist
- Evidence of land control (contract or deed)
- Preliminary or approved construction plans and specs
- Detailed, line-item budget—including soft costs and contingency
- Builder and contractor background information
- Permitting steps underway or a documented timeline
- Project pro forma with anticipated exit scenario
- Proof of liquidity (bank statements, cash reserves)
- Draw schedule proposal
- References or past project snapshots (if available)
Comprehensive submissions speed up review and reduce questions, making it easier for lenders to assess your request.
Real Estate Investor Financing FAQs
How are Lakeland new construction loans typically structured for investment properties?
Business-purpose loans in Lakeland are often based on the strength of the project, borrower experience, plans, and ability to complete and exit the investment. Exact terms vary based on project specifics.
Can first-time builders get approved for new construction financing in Lakeland?
AFI Private Lenders may review first-time builder requests, but approval is not guaranteed. Strong teams, detailed budgets, and realistic plans improve approval chances.
What items do lenders usually require during draw requests?
Typically, lenders require evidence of work completed, updated inspections, and supporting documentation—each tied to the original draw schedule and budget.
What if project costs exceed the original Lakeland construction budget?
Borrowers are expected to cover overruns with their own funds. Lenders prefer a contingency reserve and sufficient liquidity to manage unplanned expenses.
Are new construction loans available for rental projects in Winter Haven or Plant City?
Yes, eligible investors in surrounding Polk County communities may seek financing for rental or sale projects, subject to lender underwriting and local project conditions.
How important is exit planning in private construction loan approvals?
Exit planning is essential. Lenders assess whether your strategy—sale, refinance, or rental stabilization—is realistic given the project's location and market.
What can delay funding or approval in Lakeland construction loans?
Missing permits, unclear budgets, incomplete project information, or lack of demonstrated liquidity can all delay or hinder the approval and funding process.
Have a Lakeland investment property to finance?
Send the property address, requested loan amount, property type and investment plan for an initial review.