A practical guide to Lakeland fix and flip loans. Learn how inland Florida investment property financing is evaluated and what local investors should know.
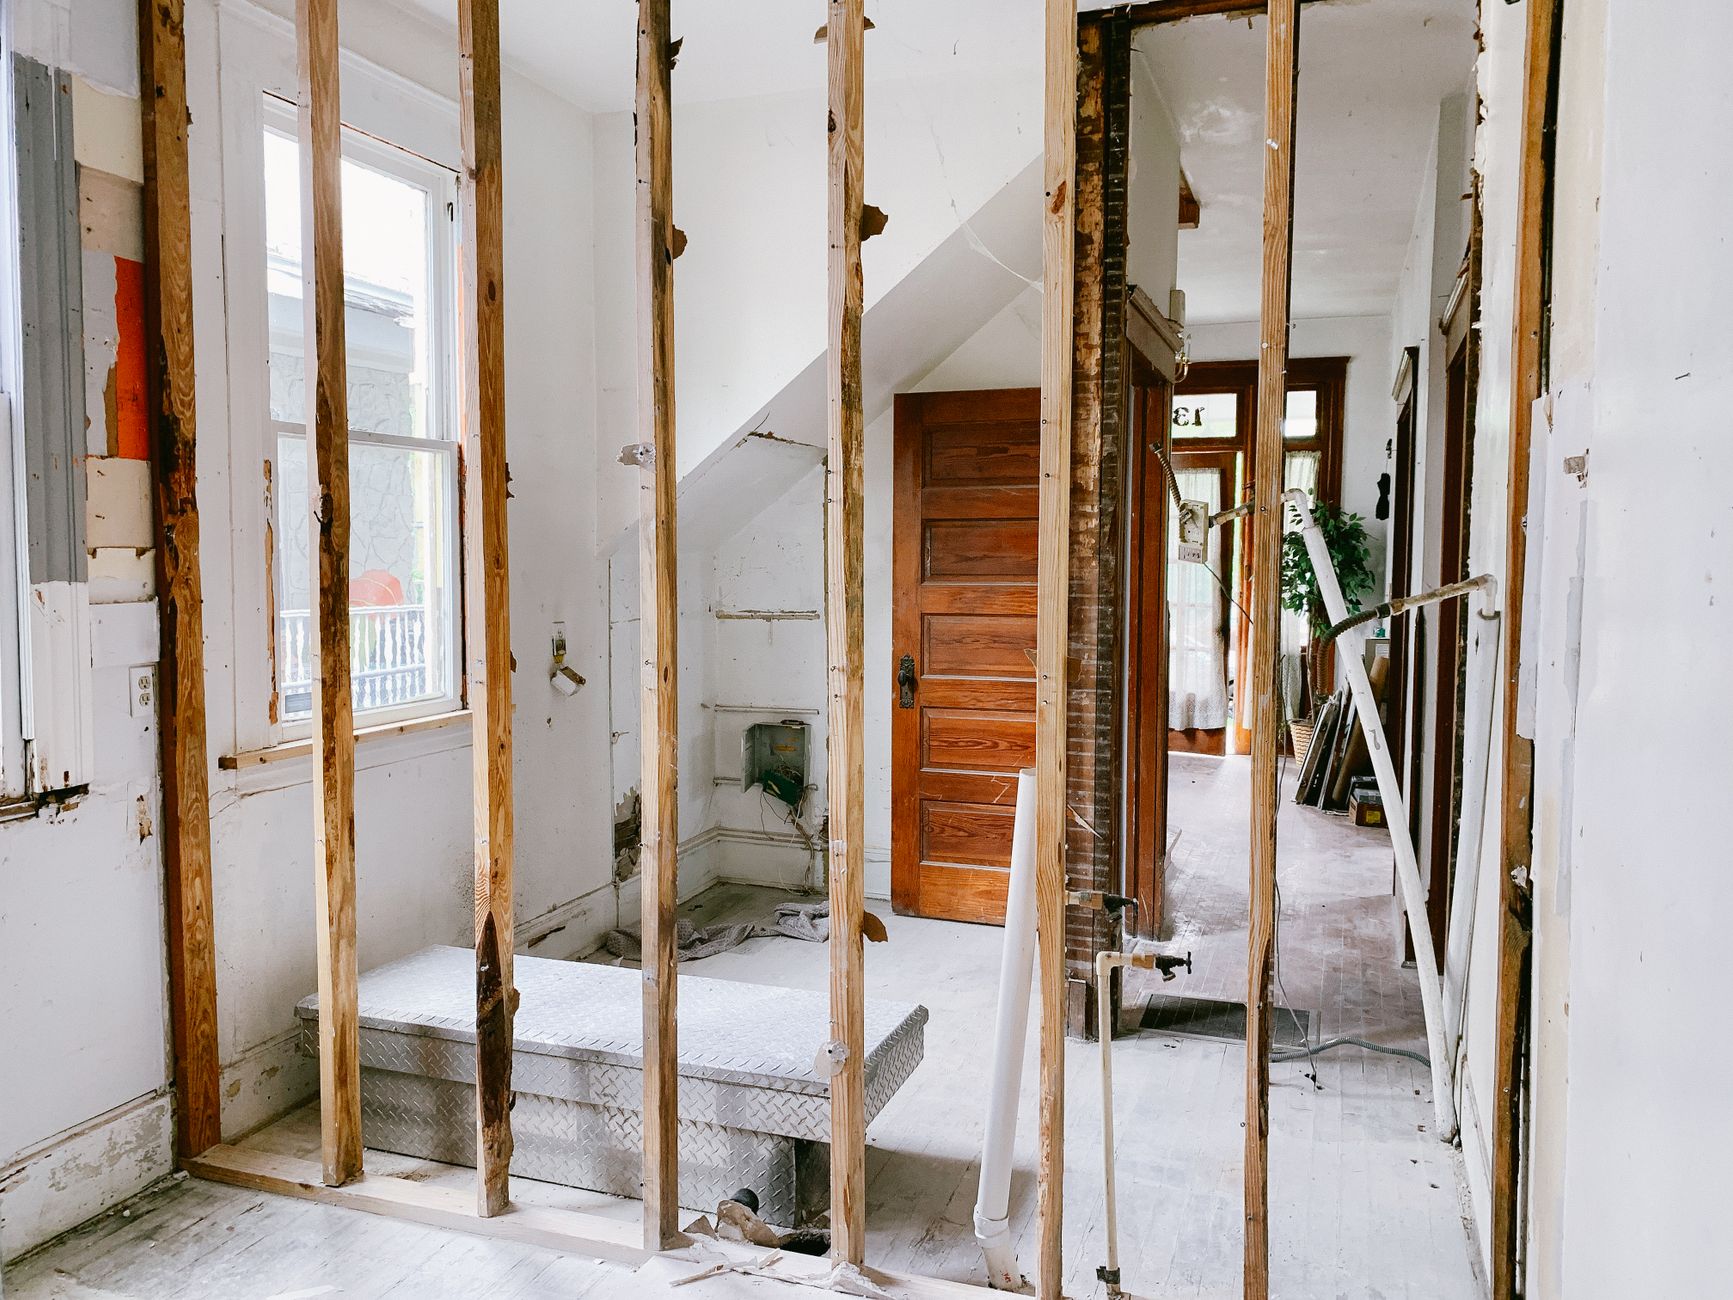
Central Florida’s gateway city, Lakeland, anchors a dynamic region where disciplined investors turn underperforming properties into profitable assets. If you’re considering a fix and flip project in Lakeland or nearby communities like Winter Haven, Auburndale, or Bartow, finding the right financing is critical to maximizing your investment’s potential.
Unlike coastal speculation, success in the Lakeland fix and flip market depends on prudent budgeting and a well-planned exit. This guide walks through how AFI Private Lenders evaluates fix and flip loan requests, what makes Polk County projects stand out, and how to present your investment plan for the best possible chance at approval.
How Fix-and-Flip Financing Is Evaluated in Lakeland
When seeking Lakeland fix and flip loans, local investors should expect a detailed underwriting process focused on the viability of the project itself. AFI Private Lenders looks beyond just credit scores, centering loan evaluation on the acquisition price, property condition, planned renovations, leverage needs, and—most importantly—a credible exit strategy. A well-presented plan outlining budget discipline and local market knowledge will help your request stand out in Polk County’s competitive landscape. Before moving forward, expect AFI's team to review the strengths of the project and the feasibility of proposed improvements—and not just your personal finances.
Purchase Price, Current Condition and Renovation Scope
For investors in Lakeland, understanding how purchase price and property condition weigh into loan decisions is crucial. AFI evaluates whether the acquisition price makes sense for comparable properties in neighborhoods ranging from central Lakeland to those in Plant City or Auburndale. Detailed estimates for repairs and improvements help substantiate the renovation scope, which is essential for both risk assessment and draw planning. Clearly document deferred maintenance, structural needs, and market-appropriate upgrades to position your request as realistic and grounded.
Why the Property and Project Can Matter More Than Traditional Credit Scoring
Unlike many lending options, AFI Private Lenders does not rely heavily on traditional credit scoring when reviewing fix and flip loans in Lakeland, Florida. Instead, the property’s location, value-add potential, and your plan for improvements are primary underwriting factors. For business-purpose loans, a clear track record of successful investments or a strong, detailed renovation plan can often outweigh a borrower's FICO score. This approach can be advantageous for experienced flippers as well as landlords expanding within Polk County, provided their project fundamentals are sound.
Rehab Budget, Contractor Planning and Construction Draws
Budget discipline separates successful Lakeland investors from hopeful speculators. AFI expects applicants to submit a realistic, itemized renovation budget, including labor, materials, contingency, and permit allowances specific to Lakeland and surrounding communities. If you rely on general contractors, subtotal labor projections, and confirm licenses for work in Polk County. Construction draw requests are kept straightforward for qualifying projects, but all are subject to loan documents, periodic inspections, and AFI underwriting. The more detailed your planning, the easier it is for lenders to track progress and release funds efficiently.
Borrower Liquidity, Contingency and Carrying Costs
Projects in neighborhoods like Winter Haven and Bartow often face surprise repairs or longer holding periods. That’s why AFI reviews each borrower’s liquidity and their plan for contingency reserves and carrying costs. Having enough capital to manage delays, fund overruns, or unexpected issues is critical—not just for loan approval, but for deal survival. Provide supporting bank statements or funding plans showing you can cover insurance, taxes, utilities, and make monthly loan payments throughout the renovation phase.
Exit Strategy: Resale, Refinance or Rental Conversion
Inland Florida investment success is as much about the exit as the acquisition. AFI Private Lenders requests a clear, realistic exit plan as a core element of all Lakeland investment property loans. Whether your strategy is reselling for profit, refinancing into a rental loan, or holding for cash flow, spell out your expected timeline and backup options. Supporting data from central Lakeland or even from solid rental markets in Auburndale can help fortify your business case and show that you understand Polk County’s cycles and buyer demand.
What to Send AFI for an Initial Review
Preparing a comprehensive loan package can accelerate your review. For Lakeland fix and flip loans, AFI Private Lenders typically requests:
- Purchase contract (or detailed property description)
- Renovation budget with clear line items
- Contractor estimates or scope of work
- Photos or recent inspections of property condition
- Borrower resume or record of completed projects (if available)
- Summary of your exit strategy and market assumptions
Organized, well-supported packets help speed up underwriting and focus review on factors that matter most in Lakeland’s market.
When Another Financing Option May Be a Better Fit
Not every Polk County project is suited for a traditional fix and flip structure. If you’re tackling extensive, multi-phase rehabs in Plant City, seeking long-term rental holds, or lack renovation experience, alternative financing routes may be advisable. AFI Private Lenders can discuss bridge loans, ground-up construction options, or alternative leverage structures for deals that don’t align with standard fix and flip models. Understanding these trade-offs ensures you apply for the program that matches your goals, property, and business plan.
Real Estate Investor Financing FAQs
Can first-time investors get approved for Lakeland fix and flip loans?
First-time investors can apply, but AFI gives significant weight to the property, project plan, and exit strategy. A strong, well-supported proposal may offset limited experience.
Does AFI require a minimum credit score for Lakeland fix and flip loans?
Traditional credit scoring is not heavily relied upon, but a full review of your financials and project is always completed. All loan approvals remain subject to underwriting.
Are construction draws complicated to manage?
AFI aims to keep draw requests straightforward and practical, tied to the submitted renovation budget and subject to inspections and underwriting requirements.
How important is the exit strategy for approval?
Exit strategy is a central underwriting factor, whether you plan to resell or refinance. A solid, data-backed plan can strongly impact approval odds.
Can I use Lakeland fix and flip loans for properties in Winter Haven or Bartow?
Yes, qualifying properties in many Polk County communities—including Winter Haven and Bartow—can be considered for these programs.
Is long-term rental financing available through AFI?
AFI offers multiple business-purpose financing options. If your focus is rental hold rather than immediate resale, ask about alternative loan programs.
What documents speed up the loan review process?
A clear purchase contract, renovation budget, contractor bids, exit plan, and documentation of borrower experience help AFI quickly evaluate your request.
Have a Lakeland investment property to finance?
Send the property address, requested loan amount, property type and investment plan for an initial review.