A practical guide to fix & flip loans in Jacksonville, Florida, detailing how projects are evaluated and what Northeast Florida investors need to prepare.
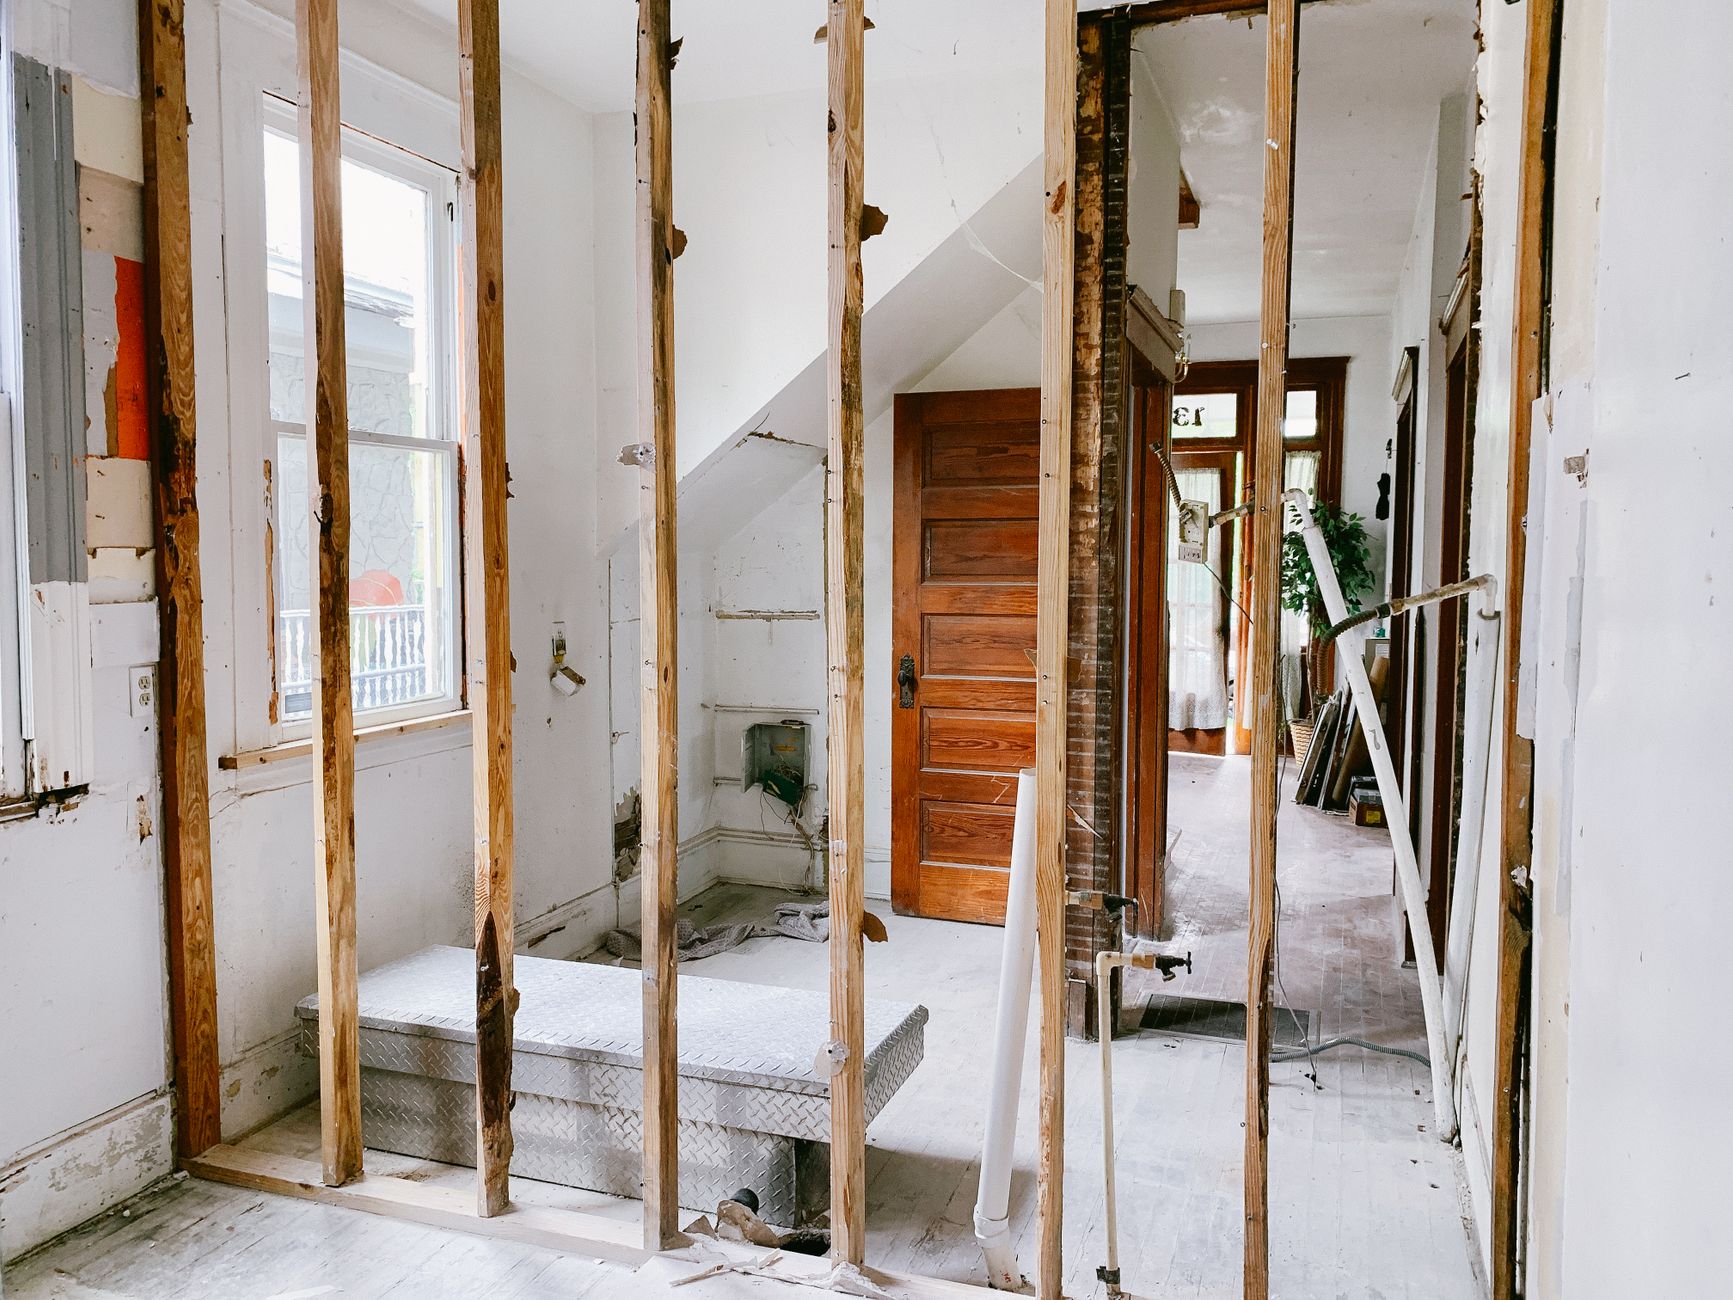
Jacksonville’s neighborhoods—from Riverside and San Marco to suburban areas like Orange Park or Atlantic Beach—offer a spectrum of value-add opportunities for real estate investors. Whether your goals are flipping single-family homes near the St. Johns River, renovating a duplex in Springfield, or repositioning a commercial property in Duval County, tailored financing is essential for getting your project off the ground.
This guide breaks down how Jacksonville fix and flip loans are assessed, what matters most to local lenders, and best practices for moving from purchase to profitable exit. Instead of taking a generic approach, you’ll find market-relevant insights for Northeast Florida projects, plus clear preparation steps for working with experienced private lenders like AFI.
How Jacksonville Fix and Flip Loans Are Evaluated
Every fix and flip project in Jacksonville or its neighboring communities is unique, and successful loan approvals reflect that reality. Private lenders, such as AFI Private Lenders, focus less on one-size-fits-all benchmarks and more on the strength of the specific opportunity. For qualifying projects, that means a thorough look at the property type, current condition, scope of work, investor’s experience level, and the anticipated exit strategy. Whether investing near Jacksonville Beach or in a core Duval County neighborhood, a tailored loan evaluation emphasizes local property dynamics and project feasibility over generic borrower metrics.
Purchase Price, Current Condition and Renovation Scope
The starting point for any Jacksonville investment property loan is the acquisition cost and the present condition of the real estate. Investors are expected to share detailed renovation plans, showing how improvements—from cosmetic upgrades in Ponte Vedra Beach townhomes to structural changes in mixed-use downtown buildings—will create value in a targeted timeframe. The more clearly you can justify your purchase price and your construction scope, the smoother the underwriting process will be.
Why the Property and Project Can Matter More Than Traditional Credit Scoring
Unlike some conventional lenders, AFI Private Lenders does not rely heavily on traditional credit scoring for qualifying fix and flip loans in Jacksonville, Florida. While the borrower’s background is reviewed as part of overall risk analysis, the main underwriting priorities are the investment property itself, the local market, and the viability of the proposed strategy. Investors with strong projects—supported by clear renovations, market analysis, and a credible exit—may find more flexibility in financing structure even if their personal credit profile is not the main driver.
Rehab Budget, Contractor Planning and Construction Draws
The rehab budget and the plan for managing contractors are under close review by Jacksonville private lenders. Lenders like AFI expect a line-item budget and a clear narrative for each phase, whether you’re upgrading kitchens in the Southside or repositioning a commercial parcel in Baymeadows. Draw requests for construction funds are kept practical, subject to the agreed loan documents, inspections, and general underwriting. A prepared borrower will detail which improvements add the most value and back up plans with qualified contractor estimates when possible.
Borrower Liquidity, Contingency and Carrying Costs
Even when leverage is available, Northeast Florida investors must show sufficient liquidity to cover down payments, up-front expenses, and the inevitable scope changes that come with renovations. A responsible fix and flip loan application includes a plan for carrying costs—such as utilities, taxes, and insurance—plus a contingency buffer for unexpected overruns. Lenders want to see that your business plan is robust enough to weather delays or cost increases, whether you’re flipping in Ortega or scaling up a multifamily project in Arlington.
Exit Strategy: Resale, Refinance or Rental Conversion
A clear exit strategy is central for any Jacksonville investment property loan. Are you looking to sell quickly in the hot Riverside resale market, refinance for a long-term hold in Mandarin, or convert to a cash-flowing rental in Atlantic Beach? AFI and other experienced private lenders will assess how realistic your timelines and anticipated valuations are, given local real estate dynamics and your previous track record. Strong exit planning, supported by comparable sales and rental estimates, makes your loan file much stronger.
What to Send AFI for an Initial Review
A successful fix and flip loan request starts with a complete and organized submission. Before contacting AFI, make sure you have the property address, purchase contract, renovation scope and budget, photos of current condition, project timeline, contractor details, and your basic business plan ready. If you’ve operated projects nearby (like in Jacksonville Beach or Orange Park), include summaries or references. This up-front preparation helps AFI provide clear feedback and appropriate loan options for your Northeast Florida investment.
When Another Financing Option May Be a Better Fit
Not every scenario suits Jacksonville fix and flip loans. If your project involves heavy new construction, highly specialized property types, or owner-occupied homes, alternative financing structures may offer better terms or processes. Likewise, new investors without a clear plan or adequate liquidity could benefit from partnerships or joint ventures until they establish a stronger track record. The right lender will provide candid feedback—whether your project fits AFI’s scope for Duval County business-purpose lending or should be matched with another resource.
Real Estate Investor Financing FAQs
Do I need perfect credit to qualify for fix and flip loans in Jacksonville?
No, traditional credit scoring is not relied on heavily for qualifying fix and flip loans with AFI. The property, project, and exit plan are emphasized.
Can I finance a rental property conversion with a Jacksonville fix and flip loan?
Yes, many investors use fix and flip loans for renovation and then refinance into long-term rental financing once the property is stabilized.
What documents are needed for an initial review with AFI?
Typical items include the address, purchase contract, renovation scope and budget, current condition photos, your project timeline, contractor info, and prior experience.
Are draws for construction work complicated?
Draw requests with AFI are intended to be straightforward and practical, subject to the loan documents, project inspections, and underwriting requirements.
Is there a minimum or maximum loan size for Jacksonville fix and flip projects?
Loan amounts depend on the individual project and underwriting. AFI evaluates each opportunity based on its merits rather than hard minimums or maximums.
Can first-time investors or builders qualify?
AFI does not guarantee approval for first-time builders. Experience is considered, but strong business plans and clear renovations can help new investors qualify.
Which areas near Jacksonville does AFI serve for fix and flip loans?
AFI provides fix and flip financing in Jacksonville, Duval County, and surrounding communities such as Jacksonville Beach, Orange Park, Atlantic Beach, and Ponte Vedra Beach.
Have a Jacksonville investment property to finance?
Send the property address, requested loan amount, property type and investment plan for an initial review.