
AFI Private Lenders recently funded a $75,000 probate-related loan for 4103 Durant Rd, Valrico. Learn how business-purpose funding works with Florida probate property loans.
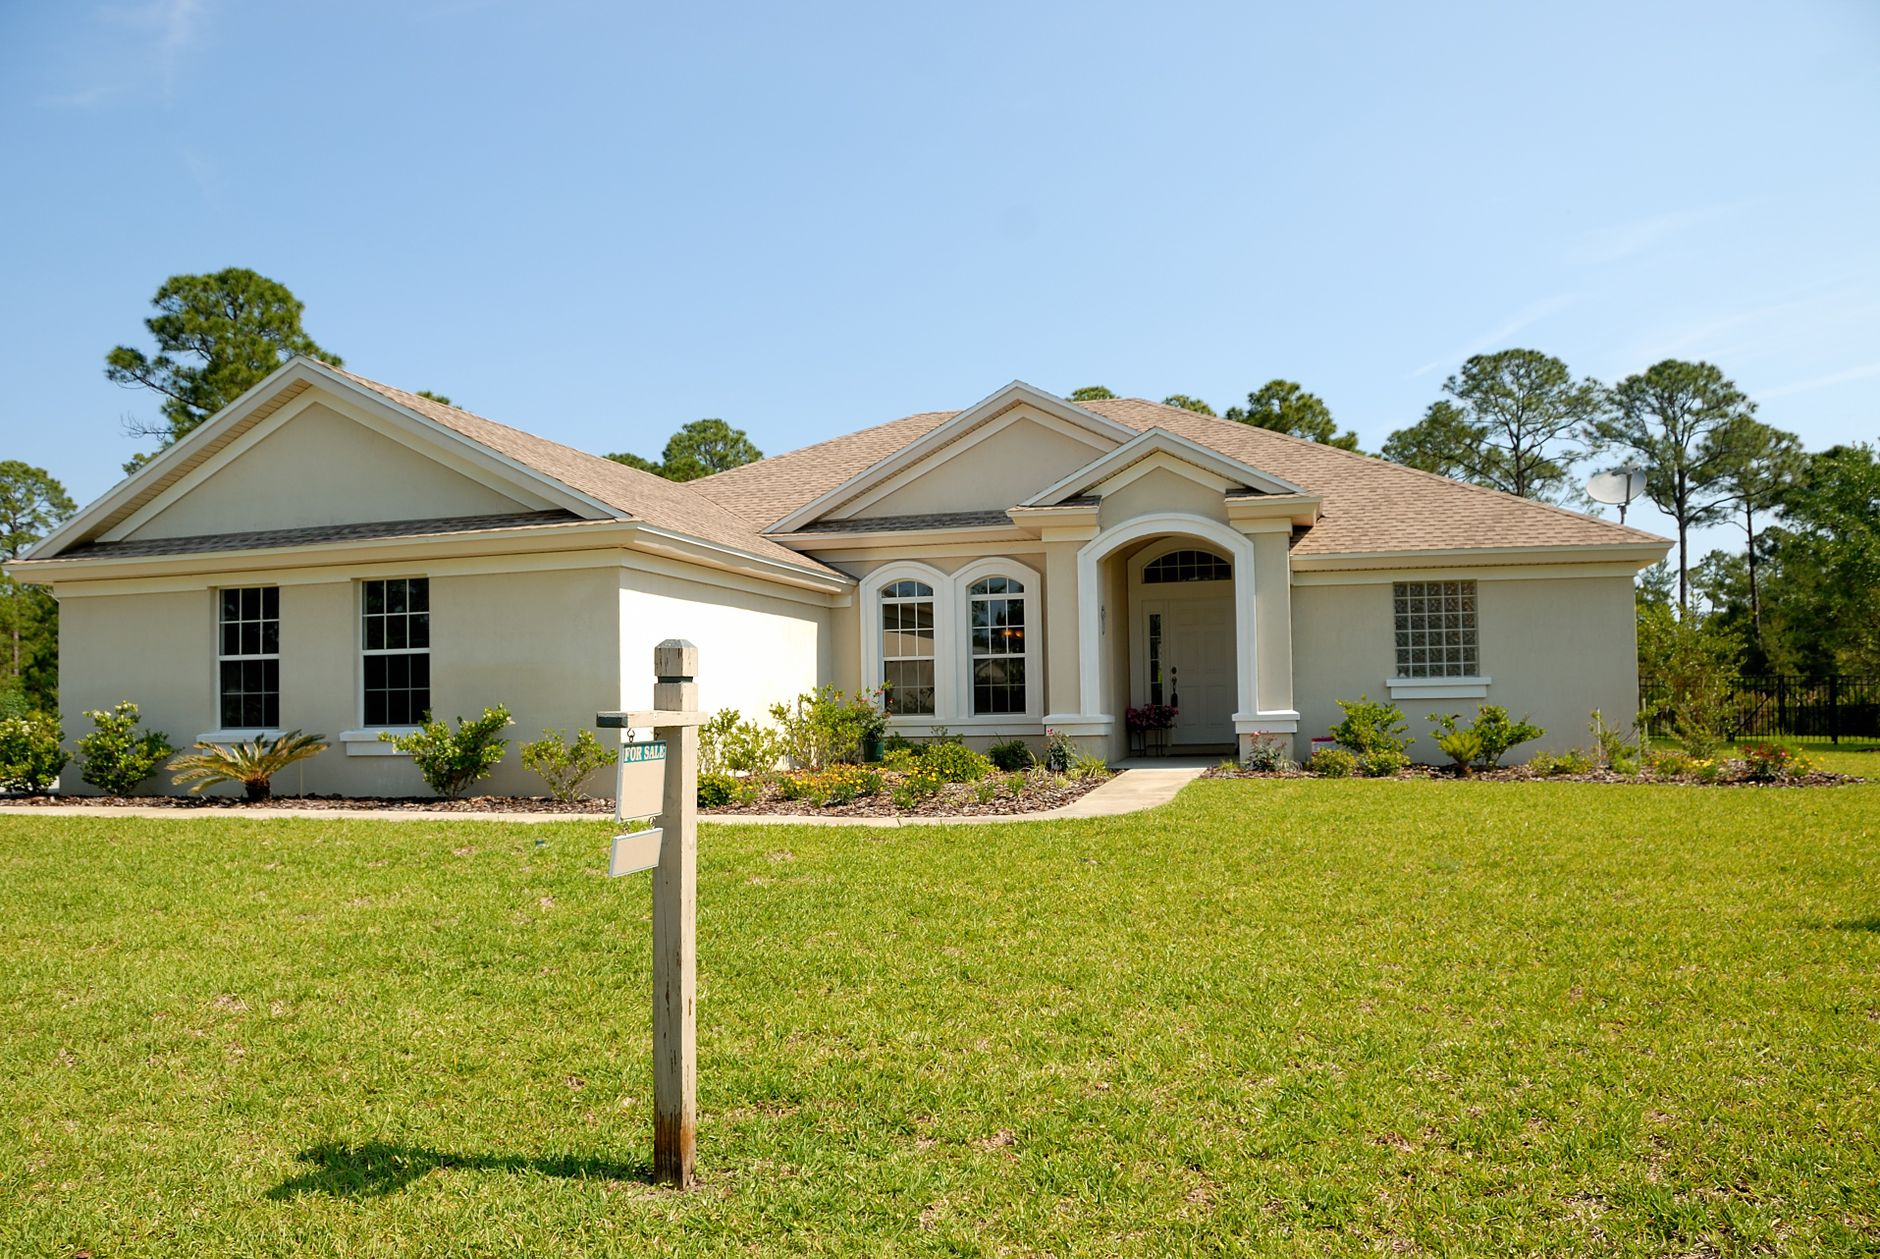
AFI Private Lenders recently completed a $75,000 real estate loan connected with a probate matter involving 4103 Durant Rd in Valrico, Florida. This loan carried a two-year term and a fixed 9.5% stated annual interest rate—specific only to this transaction, not as an open offer to every applicant.
If you're an investor, builder, or landlord in Valrico, Brandon, Bloomingdale, Riverview or nearby Tampa Bay areas considering or inheriting property involved in probate, understanding how Florida probate property loans work is essential before financing options like private money bridge loans can be properly evaluated.
AFI Funded $75,000 at 4103 Durant Rd in Valrico, FL
Highlighting a real example for Florida real estate investors, AFI Private Lenders reports funding a $75,000 real estate loan secured by 4103 Durant Rd, Valrico. This business-purpose transaction involved probate-related circumstances but does not reflect advertised rates or automatically available loan terms. The deal featured a 24-month term and a stated 9.5% annual interest rate, strictly as a documented fact about this specific loan.
24-Month, 9.5% Rate: Only This Transaction—Not an Offer or Universal Term
It's important to clarify that the 2-year term and 9.5% annual rate described above are only historical information about this particular AFI-funded loan. These terms do not represent any general offer or current program rate. Every business-purpose real estate loan application is reviewed individually by AFI, and there is no guarantee of these terms for future deals in Valrico or elsewhere in Florida.
What Makes Florida Probate Property Loans Unique?
Florida probate property loans help unlock financing for investment properties subject to or affected by probate—meaning assets that are part of a deceased person's estate being administered through Florida's legal procedures. This is different from unsecured inheritance cash advances that provide funds upfront against a future inheritance. AFI’s probate real estate loan Florida program provides business-purpose, collateral-based funding for issues like acquiring, rehabbing, or restructuring title to inherited properties located everywhere from Valrico and Brandon to Tampa and elsewhere in Hillsborough County.
Who Has Legal Authority to Borrow Against Estate or Inherited Property?
Florida laws require that only parties with established legal authority over the property can pledge or mortgage estate real estate, especially during probate. Typically, this includes the court-appointed personal representative—assuming appropriate authorization by will or court order (see Florida Statutes 733.613 and 733.608 for context). Title professionals and the estate’s probate attorney must verify exactly who, if anyone, has the right to borrow and whether additional court approval is mandated before closing. Heirs, beneficiaries or family members cannot automatically borrow against estate property simply due to inheritance expectations.
Court Authorization, Florida Homestead, and Title Exceptions
Many properties in the probate process may be protected Florida homesteads or have title exceptions affecting mortgages. Under Florida law, a homestead may pass outside the probate estate, subject to constitutional restrictions, and may not be freely mortgaged by an estate representative. Title companies and a Florida probate attorney must determine whether the property is indeed homestead, who controls it, and whether a mortgage is legally permitted. Court approval is sometimes required even when a will is present. Any investor or personal representative must secure all necessary approvals and documentation before moving forward.
How AFI and Other Private Lenders Underwrite Probate-Related Collateral
AFI Private Lenders evaluates business-purpose requests for probate property financing based on the security of the underlying real estate, the structure of the estate, the borrower's legal authority, and the likelihood of successful payoff or exit. While AFI does not rely heavily on traditional credit scoring for Florida fix-and-flip loans, collateral value, title clarity, probate status, and valid exit strategy are essential. Final leverage and approval depend on the property condition, marketability, and all probate/title issues being resolved to the satisfaction of counsel and the title agent.
Essential Documents and Counsel Review for a Florida Probate Real Estate Loan
Closing a probate-related loan in Florida requires a higher level of diligence than ordinary real estate transactions. Expect to provide:
- Title report showing current ownership and encumbrances
- Letters of administration/court order appointing the estate representative
- Confirmation of powers granted (e.g., will and/or court authorization per Fla. Stat. 733.613)
- Florida probate attorney’s review and written opinion when required
- Insurance and verification of property status (especially homestead concerns)
These are reviewed by the lender, closing attorney, and title company before a loan can close. Borrowers should consult with their own Florida-licensed counsel to confirm eligibility and compliance.
How to Request a Probate Property Loan Review from AFI
If you are evaluating sale, buyout or improvement scenarios for an estate or inherited investment property anywhere in Hillsborough County or the greater Tampa Bay area, you may submit a business-purpose scenario for review by AFI Private Lenders. Every proposal is considered case-by-case; eligibility depends on real estate collateral, probate status, confirmed authority, exit strategy, and property suitability. There is no guarantee of approval. Be prepared to provide documentation and to work with your own attorney and title professional to clear any probate or legal title issues. For qualifying borrowers, working with experienced private lenders like AFI may unlock timely solutions for complex estate property needs that traditional banks typically cannot address.
Mini-Case: Hypothetical Probate Loan Scenario in Valrico
Consider an investor is named personal representative of a non-homestead property in Valrico, confirmed by the Florida probate court. The estate needs funds to repair and reposition the property for resale. After consulting with a probate attorney and title company, the representative shows clear power to mortgage. The investor approaches a private lender for a $100,000 bridge loan secured solely by the Valrico property. The lender reviews the title, verifies probate court orders, and requests a defined exit plan (e.g., listing for sale). This hypothetical example illustrates the sort of scenario that may qualify for a Florida probate property loan—whereas deals lacking probate authority or with unresolved title/homestead concerns typically cannot move forward until fixed.
Checklist: Documents and Professionals Needed Before Applying
- Current title report and property legal description
- Letters of administration or court order naming power-holder
- Attorney opinion of authority to mortgage (if required)
- Original will (when available) and probate court documentation
- Insurance information and property condition disclosure
- Written exit strategy (sale, refinance, payout of estate, etc.)
Trade-Offs: When a Probate Real Estate Loan May or May Not Make Sense
Probate loans secured by real property in Florida can provide flexible solutions for estate processes that demand liquidity, repairs, or buyouts. However, they are not ideal for every estate. If court approval is difficult, probate timing is uncertain, or the property is subject to homestead exemptions, alternative strategies (such as waiting for probate completion or selling as-is) could be preferable. Additionally, heirs needing only personal cash advances without business or investment purposes may not qualify for secured private money loan programs. Every scenario should be discussed with estate counsel and, if needed, a private lender to weigh risks and rewards before proceeding.
Real Estate Investor Financing FAQs
What is a Florida probate property loan?
A Florida probate property loan is business-purpose financing secured by investment real estate affected by probate—typically requiring legal authority and approval before the loan closes.
Can any heir get a loan against estate property in Florida?
No. Only individuals or entities with legal authority (such as a personal representative) and, when necessary, court approval can borrow against probate property in Florida.
How is a Florida probate loan different from an inheritance advance?
A probate real estate loan is secured by a property and used for business or investment purposes. An inheritance advance is an unsecured payment against an expected future inheritance, which most private lenders do not offer.
Do all probate properties require court approval for a mortgage?
Not all, but many do. Whether court approval is required depends on the will, Florida law, court orders, and whether the property is a protected homestead.
What documents does AFI need for a probate-related real estate loan?
Title report, probate court orders, proof of authority to mortgage, attorney's opinion, insurance, and details on property condition and exit strategy are typically required.
Does AFI guarantee a specific rate or approval for probate property loans?
No. Each loan is reviewed on its own merits. AFI does not advertise universal rates or guarantee approval for any applicant or property.
Is AFI’s $75,000 Valrico transaction available to everyone?
No. The $75,000, 2-year, 9.5% loan at 4103 Durant Rd, Valrico is a documented historical example, not a general offer or standard available term.
Have a Valrico investment property to finance?
Send the property address, requested loan amount, property type and investment plan for an initial review.