Discover how real estate investors and builders can navigate West Palm Beach new construction loans with a tailored guide focused on leverage, budget, and exit strategy.
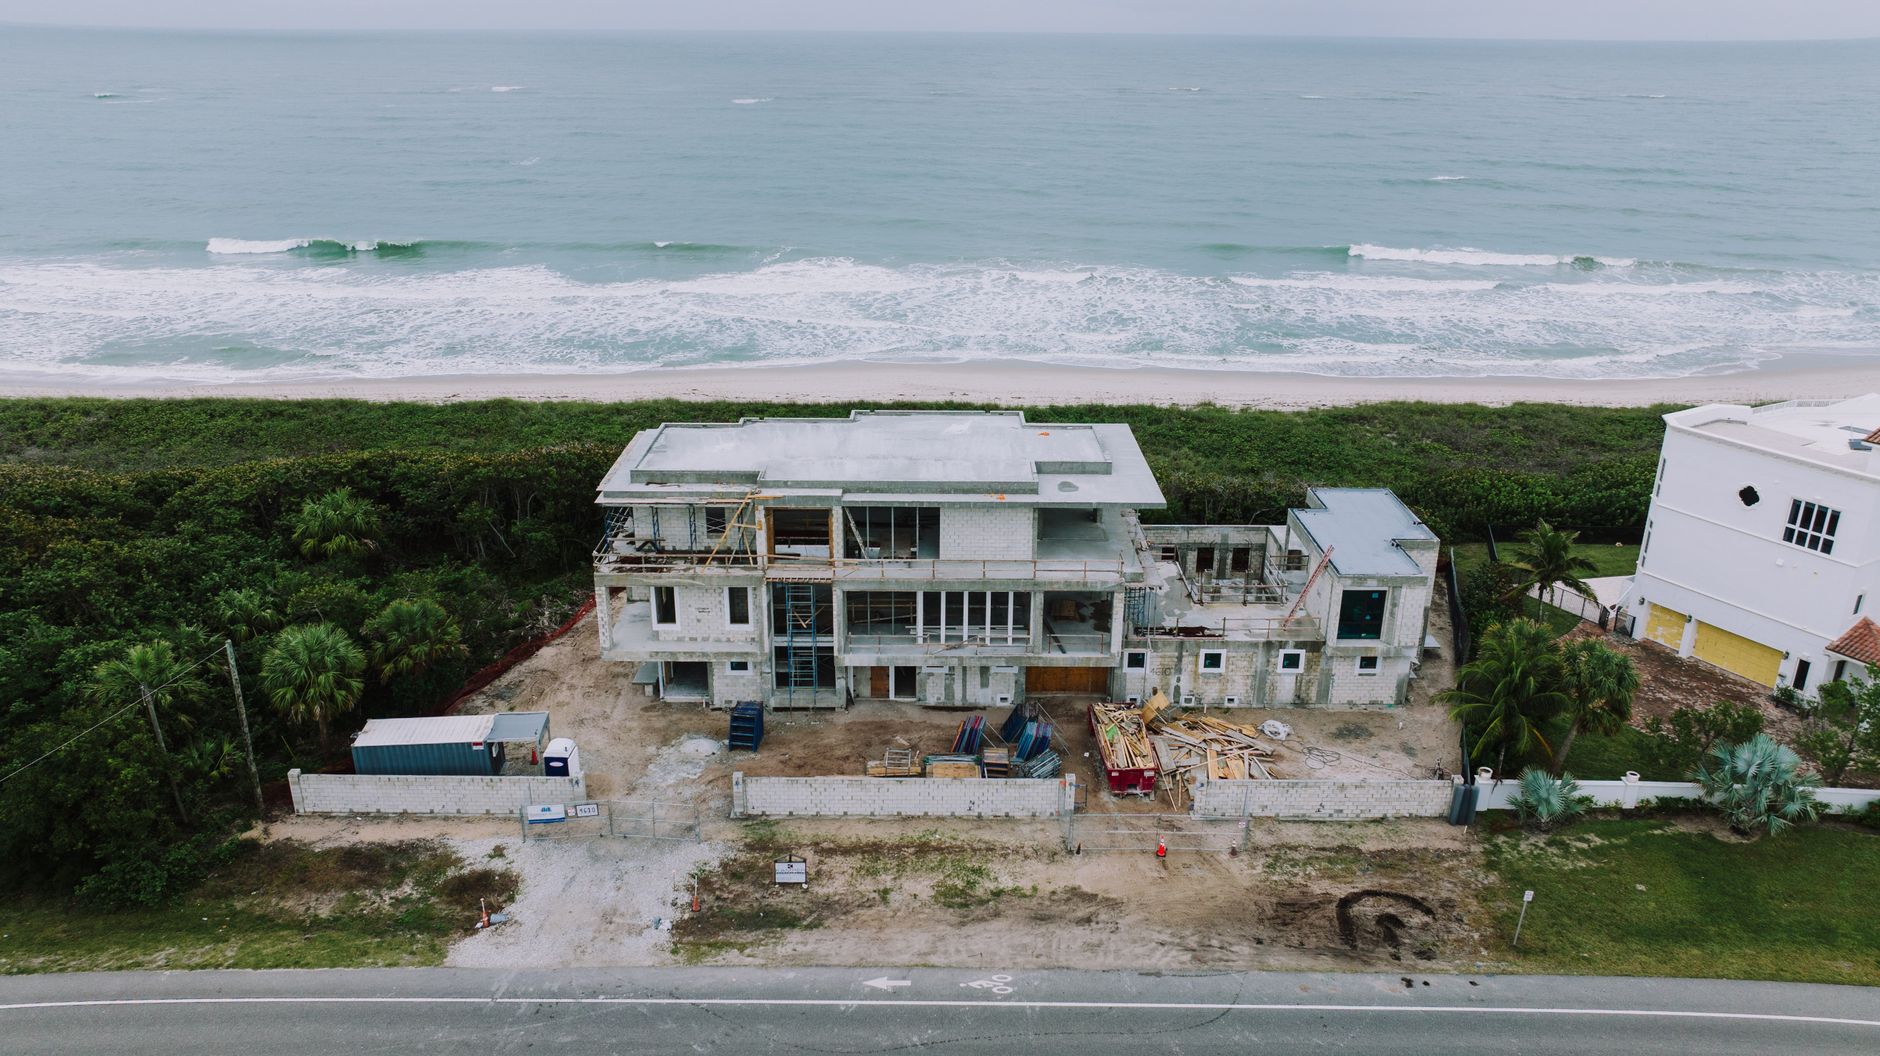
West Palm Beach and the greater Palm Beach County area are prime targets for investors seeking new construction opportunities—from infill lots in Lake Worth Beach to scattered site builds in Wellington. Successful new construction projects require more than just a strong location and ambitious plans. Understanding lender expectations for leverage, team qualifications, and overall planning is critical for securing investment property loans in South Florida’s dynamic market.
This guide unpacks the essential factors for qualifying and structuring West Palm Beach new construction loans, focusing on practical steps investors, developers, and builders should consider for both residential and commercial projects. Whether you’re exploring your first ground-up build or scaling your portfolio, using a private lender like AFI Private Lenders can help convert plans into profitable realities—if approached strategically.
What Makes a Ground-Up Construction Request Financeable?
Lending on ground-up new construction in West Palm Beach requires a careful balancing of risk and reward for both borrower and lender. A financeable request typically demonstrates a clear project vision, defined exit strategy, capable team, and the financial flexibility to manage unexpected hurdles. Unlike a fix-and-flip loan, which may rely on a property’s as-is value, new construction lending typically starts with vacant land or teardown sites—meaning the entire value must be created during the build. AFI Private Lenders evaluates investment opportunities based on project strength, realistic timelines, and the strength of both the asset and the group spearheading the work. The goal is to align investor capital, local demand, and a payoff strategy that works in South Florida’s fluctuating market conditions.
Land, Plans, Permits and Project Readiness
Lenders want to see projects in West Palm Beach and the surrounding areas that are genuinely ready to move forward. Ideally, land should be secured—either already owned or under contract. Clear design plans and at least a preliminary set of construction drawings should be available. Municipal permitting is often the biggest variable in Palm Beach County communities such as Riviera Beach or Royal Palm Beach; demonstrated progress toward approvals shows readiness and reduces delays. Lenders may scrutinize how prepared an investor is to respond to local code enforcement or neighborhood requirements unique to each city. Fully packaged submissions typically include land details, architectural plans, permit status updates, and a realistic construction timeline mapped to South Florida’s seasonality and permitting cycles.
Builder, General Contractor and Project-Team Considerations
A strong project team is a core requirement for new construction loans West Palm Beach Florida investors pursue. Lenders often evaluate builder and contractor resumes, looking for experience with similar projects in South Florida’s market climate. Even first-time developers may be considered if they partner with reputable general contractors or demonstrate extensive real estate or construction experience elsewhere. The organizational structure—whether a single managing member or a formal development partnership—and the clarity in roles and responsibilities can be especially important for projects with multiple investors. The credibility and reputation of the builder or GC often serve as a risk mitigant, providing confidence that the project can overcome West Palm Beach’s inevitable construction challenges.
Budget Detail, Contingency and Borrower Liquidity
Accurate and transparent budgeting is critical for West Palm Beach investment property loans. Detailed budgets break down the full construction cost, labor, materials, soft costs, and a contingency line to cover overruns or surprises. Private lenders like AFI typically seek evidence that the borrower has adequate liquidity—not just for the down payment and fees, but also to handle delays, change orders, and unseen costs during West Palm Beach’s rainy season or labor shortages across Palm Beach County. Underwriting may emphasize borrower reserves and the logic behind each line item in the budget. Projects with well-supported contingencies and realistic timelines tend to be viewed as more financeable, especially for higher-leverage requests where the borrower is taking a more aggressive position.
How Construction Draws Work After Closing
Once a new construction loan closes, funds are typically released in stages—so-called “draws”—as work progresses. AFI Private Lenders helps keep the draw process straightforward for qualifying transactions, though all draws are subject to loan documents, inspections and underwriting. Investors can generally expect to submit documentation of completed work and incur third-party inspections prior to each draw. The goal of a clear draw schedule is to keep the project funded and moving forward, while protecting all parties against cost overruns or non-performance. For those building in West Palm Beach, where weather and subcontractor schedules can impact timelines, proactive documentation and communication with the lender are key to smooth progress through all draw phases.
Schedule Risk, Cost Overruns and Change Orders
Every new construction project in Palm Beach County faces some degree of schedule risk, whether due to material shortages, permitting holdups, or unforeseen circumstances—particularly for coastal sites where environmental rules may apply. Lenders closely evaluate how the builder plans to manage these variables. Change orders and cost overruns are a fact of life, not an exception. Communicating potential issues early and having a plan for covering shortfalls—through contingency funds or additional liquidity—can help prevent project disruption and foster lender confidence. Private lenders may be more flexible than traditional banks when reasonable explanations and solutions are provided, but chronic budget or timeline problems can jeopardize leverage for both the current and future deals.
Sale, Refinance and Rental-Stabilization Exits
One of the most scrutinized factors in West Palm Beach new construction loans is the payoff or exit strategy. Investors targeting spec home sales, multifamily rentals in Wellington, or commercial lease-up in the urban core must clearly articulate how and when the construction loan will be repaid. Likely exits include sale of finished property, long-term rental with stabilization refinance, or a structured buyout by another investor. Lenders will want realistic assumptions about sales timing, rent projections, or refinance capacity based on current Palm Beach County trends. Unclear or speculative exits can reduce leverage or disqualify otherwise promising deals. The more concrete and data-driven the exit plan, the more confidence lenders like AFI have in funding the build.
A Construction-Loan Submission Checklist
Organizing a clear and thorough submission is one of the most effective ways to move a new construction loan forward. West Palm Beach private lenders typically want to see:
- Land contract, title, or proof of ownership
- Project plans, drawings, renderings
- Permit status, with updates or evidence of approvals in process
- Detailed construction budget and timeline, showing contingencies
- Builder/GC resumes and license details
- Evidence of borrower liquidity to cover costs and overruns
- Comprehensive exit strategy with market assumptions
- Entity documents, insurance evidence, and schedule of real estate owned
A robust submission anticipates questions and demonstrates both market awareness and attention to detail. Investors working with AFI Private Lenders can expect experienced input throughout the process but should be prepared to address all facets of the loan assessment—not simply provide raw documents.
Real Estate Investor Financing FAQs
Can first-time builders qualify for new construction loans in West Palm Beach?
First-time builders may be considered if the overall project, team, and exit strategy are strong, but approval is not guaranteed. Experience and proper preparation help.
What leverage is available for West Palm Beach new construction loans?
Eligible projects may qualify for significant leverage, depending on project strength, team, budget, and market conditions. Exact terms are determined case by case.
How are construction draws managed by AFI Private Lenders?
Construction funds are released in stages after closing, subject to inspections, project milestones, underwriting, and compliance with loan documents.
What documentation is needed to apply?
Borrowers should provide detailed budgets, plans, permit verification, proof of liquidity, builder/GC credentials, and a concrete exit strategy, among other items.
Is traditional credit scoring a major factor for new construction loans?
Traditional credit scoring is not relied on heavily for fix-and-flip loans, but lenders still assess overall financial stability and ability to execute the business plan.
Do I need permits in hand to apply for a construction loan?
Permit progress should be documented, but projects at different stages of readiness may be considered. The further permits are along, the smoother underwriting may go.
Can loans be used for commercial or mixed-use properties?
AFI Private Lenders reviews business-purpose loans for a range of real estate investment types, including residential, commercial, and mixed-use ground-up construction.
Have a West Palm Beach investment property to finance?
Send the property address, requested loan amount, property type and investment plan for an initial review.