Discover how West Palm Beach fix and flip loans are evaluated, from property criteria and renovation budgeting to local exit strategies for South Florida investors.
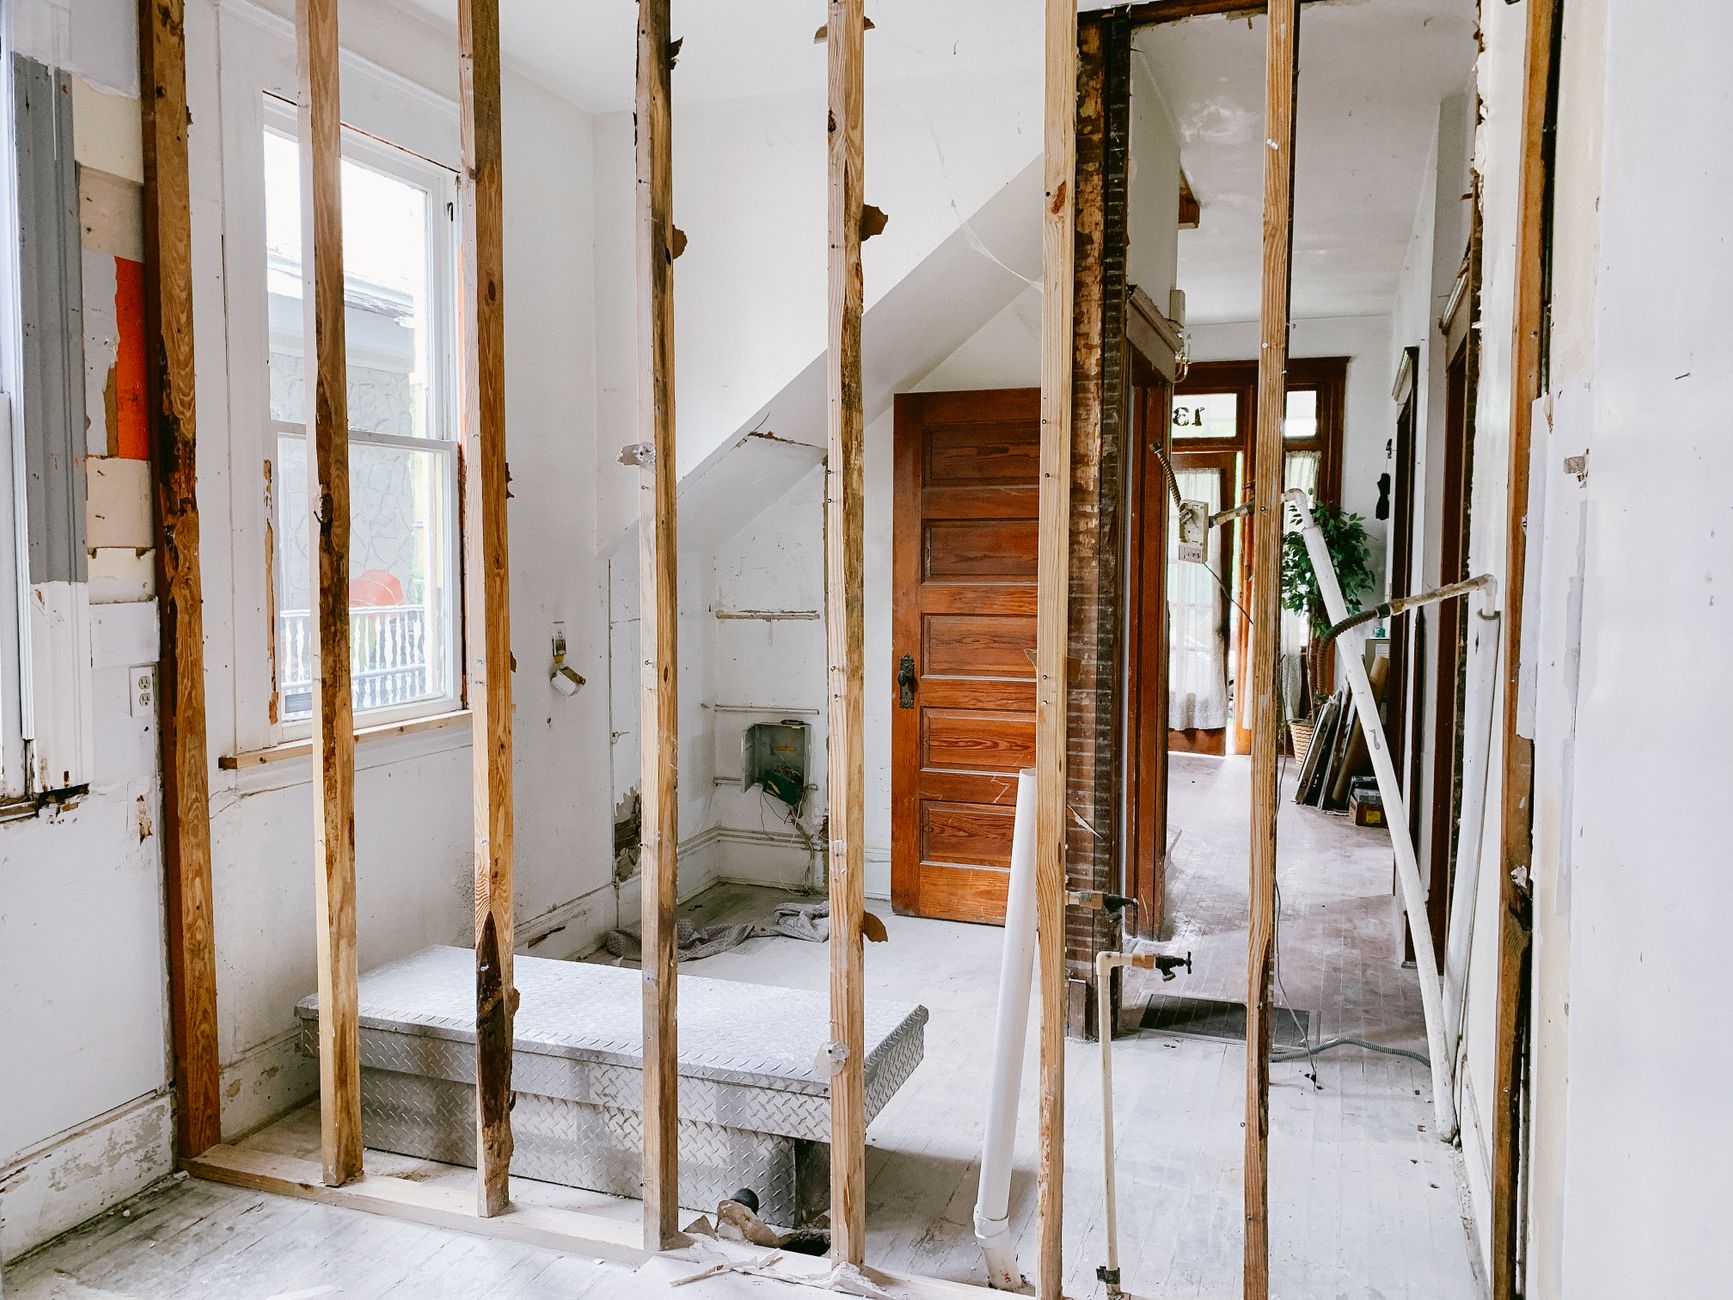
Fix and flip investments in West Palm Beach, Wellington, and throughout Palm Beach County can offer strong opportunities for real estate entrepreneurs who know the local landscape. Securing the right financing is a key part of making these transactions successful—and not all fix and flip loans are evaluated in the same way.
This guide explains how West Palm Beach fix and flip loans from private lenders like AFI are assessed, what investors need to prepare, and how the unique factors of South Florida projects shape the lending process. Understanding these elements can help improve your access to practical leverage, align your project plan, and keep your flip on track from purchase to payoff.
How West Palm Beach fix and flip loans are evaluated
For investment properties in West Palm Beach or nearby communities such as Riviera Beach and Lake Worth Beach, fix and flip loan requests are evaluated through a blend of asset-specific and borrower-specific considerations. Local private lenders like AFI focus on the property's current value, renovation plans, investor experience, and intended exit strategy. The goal is to ensure the investment makes sense based on the local submarket trends and the specifics of your project—not just a traditional credit profile.
Purchase price, current condition and renovation scope
One of the first things lenders review for Palm Beach County real estate investor financing is the purchase price and the home's as-is condition. West Palm Beach listings can range widely from historic craftsman bungalows in El Cid to concrete block homes in Northwood. Lenders pay close attention to the property’s potential—both its challenges and upside. A detailed scope of work, including all renovations planned, helps assess whether the projected after-repair value (ARV) supports the requested leverage and the business plan for the project.
Why the property and project can matter more than traditional credit scoring
Unlike many bank-originated loans, West Palm Beach private lenders like AFI do not rely heavily on traditional credit scoring for qualifying fix and flip loans. Instead, the focus is on the asset itself and your proposed project. A clear renovation plan, understanding of local market dynamics, and evidence of similar successful investments can weigh more heavily in the review than a high credit score alone. This approach is especially important in South Florida, where property values, renovation needs, and exit timelines can differ considerably block by block.
Rehab budget, contractor planning and construction draws
An actionable, line-item rehab budget is essential. Lenders want to see that you’ve accounted for labor, materials, holding costs, and have a strategy for managing contractors. In West Palm Beach and neighboring areas like Royal Palm Beach, experienced trades and general contractors may be in high demand, which can impact timelines. AFI structures construction draw requests to be straightforward and practical for qualifying projects. Draws are subject to signed documentation, inspections, and ongoing underwriting, so a well-organized process on your end—supported by local contractor relationships—can facilitate smoother funding throughout the rehab.
Borrower liquidity, contingency and carrying costs
Lenders will typically consider the investor's available liquidity—not just for the initial purchase, but also reserves for unexpected costs and carrying expenses during the renovation period. West Palm Beach’s competitive market, seasonal fluctuations, and hurricane risks underscore the need for solid contingency planning. Providing evidence of adequate reserves can help strengthen your financing request and demonstrate your readiness to navigate potential delays or cost overruns.
Exit strategy: resale, refinance or rental conversion
Fix and flip projects in Palm Beach County may end with a rapid resale, a longer-term rental conversion, or a strategic refinance. Lenders want to see a realistic exit plan tailored to local market conditions—such as marketing to end-users in downtown West Palm, targeting landlords in Wellington, or preparing to refinance into a rental hold if resale opportunities shift. Even when the plan is to resell on the open market, including a backup rental or refinance strategy can reassure lenders that you’re prepared for changes in the South Florida market cycle.
What to send AFI for an initial review
To begin the process with AFI Private Lenders, prepare the property's address, purchase contract, preliminary scope of work, estimated budget, and a summary of your experience. Sharing photos of current conditions, recent sales in the neighborhood, and planned upgrades for your West Palm Beach fix and flip loan request can accelerate the review. While traditional credit reports may still be pulled, the central focus for qualifying is your business plan, property details, and how you intend to leverage the asset.
When another financing option may be a better fit
Not every investment project or investor profile is best served by a traditional fix and flip loan. If you’re new to construction in Palm Beach County, seeking 100% financing, or planning a long-term buy-and-hold from the start, other private loan structures or capital partners might make more sense. For extensive ground-up projects or unique commercial repositionings in places like Riviera Beach, asset-based bridge lending or tailored equity partnerships may give you the flexibility you need. Discuss your goals with AFI or consult local investment advisors before committing to a loan program.
Real Estate Investor Financing FAQs
How quickly can West Palm Beach fix and flip loans be approved?
Approval timelines depend on the completeness of your documentation, property specifics, and current underwriting volume. Rapid reviews are prioritized, but each situation varies.
Is traditional credit scoring required for fix and flip loans in Palm Beach County?
Traditional credit scoring is not heavily relied on for qualifying fix and flip loans; project plan, property, and exit strategy are central underwriting factors.
What kind of renovation details are needed for a loan request?
A clear, itemized budget and detailed scope of work—covering all planned improvements—help lenders understand your project and estimate after-repair value.
Can I use West Palm Beach fix and flip loans for properties in Lake Worth Beach or Wellington?
Yes, AFI provides business-purpose real estate financing throughout Palm Beach County, including Lake Worth Beach, Wellington, and other surrounding communities.
Why does AFI require information about my liquidity and contingency plans?
Lenders want assurance that you have reserves for unexpected costs or delays, which helps reduce risk to both the borrower and lender during the flip project.
What if my project is a ground-up construction or commercial repositioning?
Fix and flip loans are typically best suited for renovation projects, not ground-up builds or major commercial transformations. Other loan types may be better suited.
Have a West Palm Beach investment property to finance?
Send the property address, requested loan amount, property type and investment plan for an initial review.