Explore how Vero Beach fix and flip loans are evaluated for Treasure Coast investment properties. Learn to prepare deals that meet local market challenges.
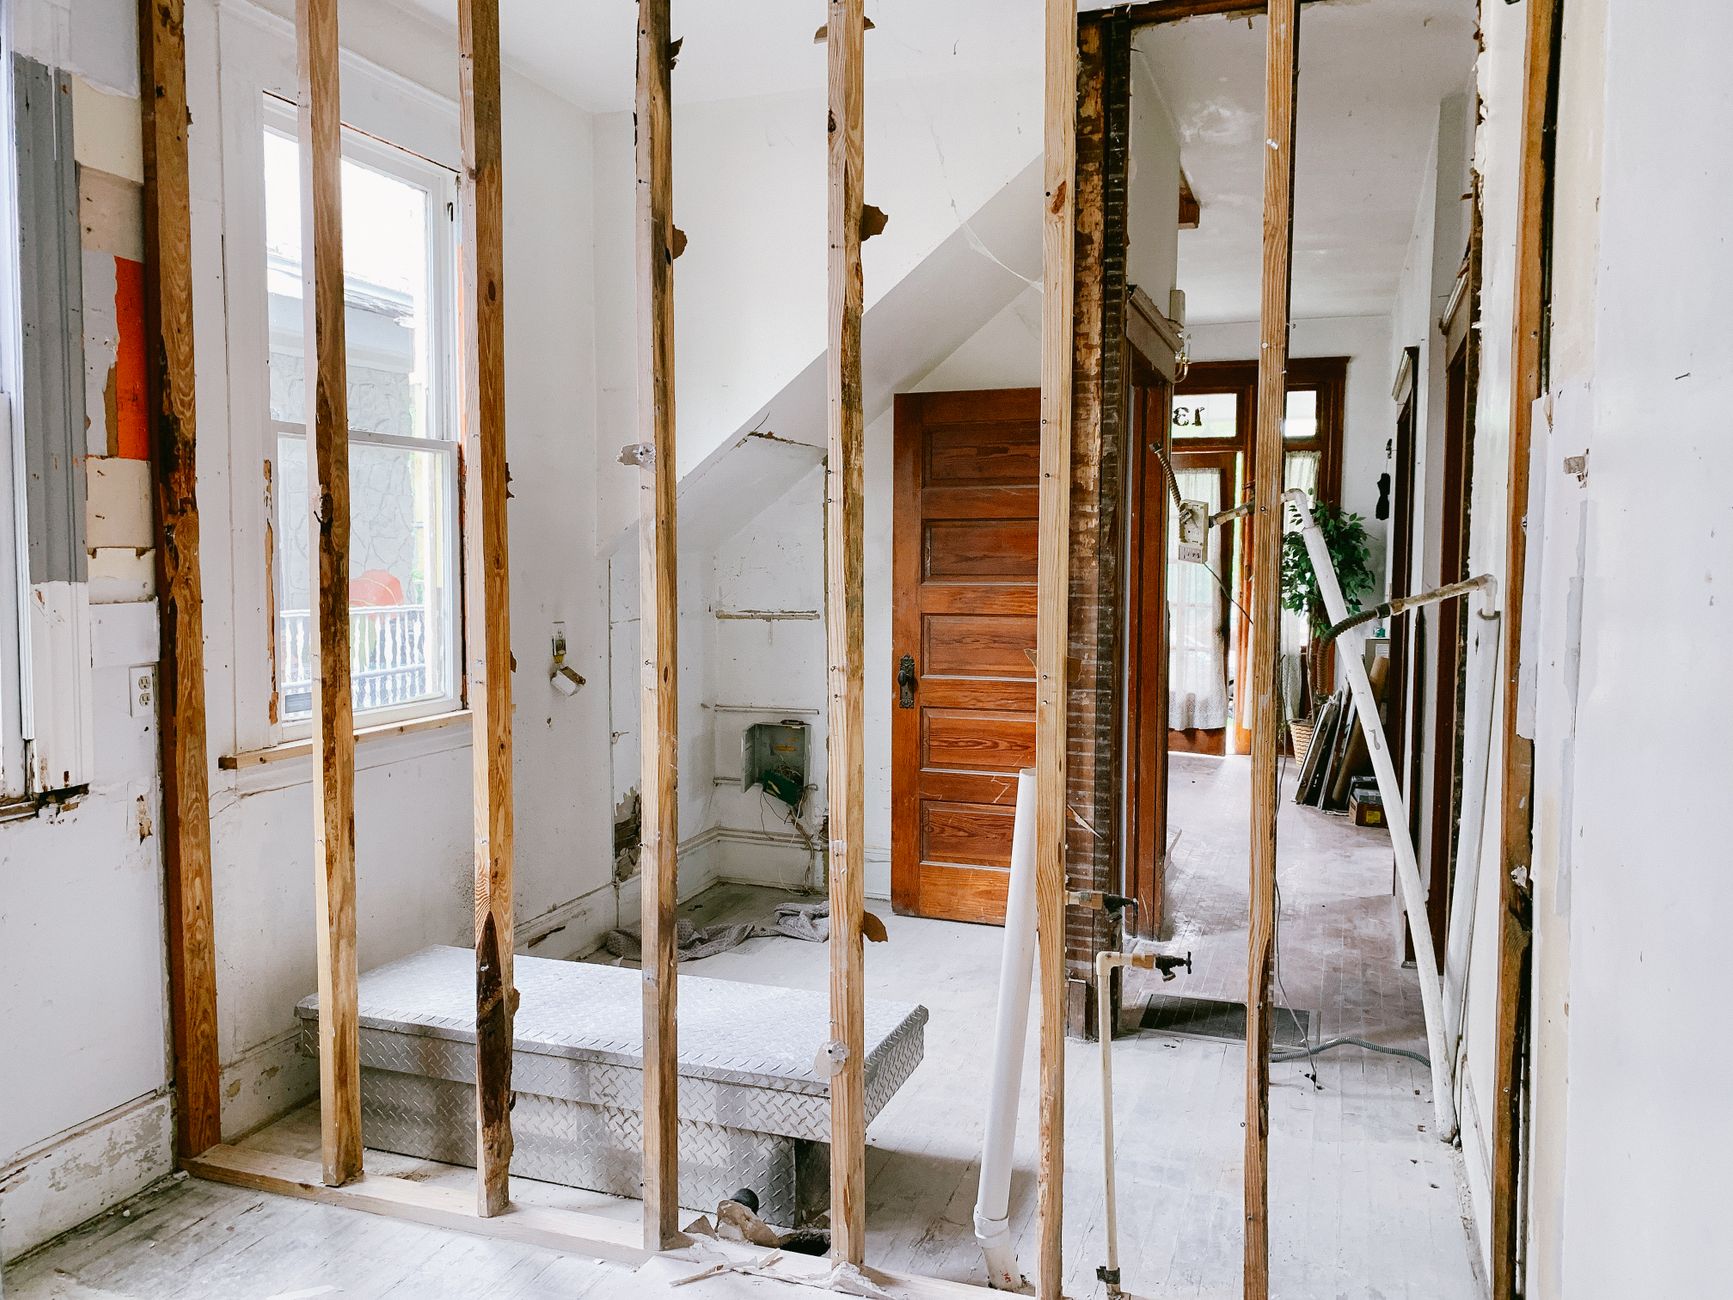
The Vero Beach real estate market, nestled along Florida's Treasure Coast, draws property investors seeking strong upside from distressed and value-add opportunities. For those targeting renovations in Indian River County, finding the right fix and flip financing often requires more than just a promising purchase price.
Vero Beach fix and flip loans reward thoughtful planning, realistic budgets, and well-developed exit strategies. This guide details what local investors should expect when preparing projects for review by private lenders like AFI, with a specific focus on local property conditions, insurance realities, and exit outcomes unique to the Treasure Coast.
How Vero Beach fix and flip loans are evaluated
When seeking fix and flip loans in Vero Beach, Florida, investors quickly find that each application is evaluated on several interconnected factors, not just a generic credit score. AFI Private Lenders, for example, focuses on the property itself, the scope of improvements, the investor's experience and background, leverage requested, proposed rehab budget, and the clarity of the exit strategy. Whether you’re searching for opportunities in Vero Beach, Sebastian, or neighboring Fort Pierce, the underlying fundamentals of the deal and its documentation matter most.
Purchase price, current condition, and renovation scope
The start of any strong fix and flip proposal is an honest look at the property's current shape and acquisition cost. Treasure Coast homes, particularly in Vero Beach neighborhoods like Central Beach or Gifford, may present hidden challenges ranging from aged roofs to unique insurance requirements after a storm. Clear documentation—recent pictures, inspection reports, and a well-developed repair list—forms the basis of any feasible investor loan proposal. Lenders want to see that the renovation plan aligns with local market standards and resale demand, especially since Indian River County's coastal climate can affect build timelines and cost assumptions.
Why the property and project can matter more than traditional credit scoring
Unlike bank options that focus heavily on a borrower’s FICO score, private lenders like AFI evaluate the strength of the Vero Beach property, the scope of renovations, experience level, and the overall project plan. This project-forward approach can help experienced investors in areas like Fellsmere or Port St. Lucie qualify for financing, provided the underlying deal structure and documentation make sense. While credit is reviewed, a strong property, conservative leverage, and sound budgeting often carry more weight in the underwriting process.
Rehab budget, contractor planning, and construction draws
In Vero Beach and throughout Indian River County, construction costs can shift with labor availability and material supply. A detailed, realistic rehab budget—broken down by trade and line item—is essential. Lenders such as AFI prioritize both the sufficiency and clarity of these budgets when reviewing investment property loans. For approved projects, construction draws are designed to be straightforward, subject to the loan documents, inspections, and typical underwriting requirements. Strong contractor planning, permits, and clear communication help avoid project delays—especially important if working on renovation projects during hurricane season or in historic districts near the beachside.
Borrower liquidity, contingency, and carrying costs
Seasoned Treasure Coast investors know unexpected costs—especially for insurance, taxes, or utilities—can arise during rehab. Lenders review available cash reserves, factoring in both contingency buffers and cost overruns. Demonstrating the ability to make loan payments and cover carrying costs during the renovation gives confidence to private lenders that, even if the sale or refinance is delayed, the project remains viable and is less likely to see distress. This is crucial in dynamic neighborhoods across Vero Beach and Sebastian, where absorption rates and holding periods can vary.
Exit strategy: resale, refinance, or rental conversion
A clear, realistic exit strategy is central to any fix and flip loan review. Vero Beach investors typically plan to sell upon completion, but changing market conditions may call for refinance, a temporary rental holding period, or even full conversion to a long-term rental. AFI evaluates each scenario based on market comparables, likely selling windows, and the borrower’s network to execute on time. Investors working in Indian River County communities like Fellsmere or Port St. Lucie should show real exit alternatives in their project summary, especially if targeting unique property types or price points.
What to send AFI for an initial review
To move a Vero Beach fix and flip project forward, submit a concise project package: purchase contract (or listing), property info, renovation budget, contractor plan, comparables, and your experience summary. AFI Private Lenders will then review the details with a focus on property condition, scope, requesting leverage, contingency funding, and the full proposed exit path. The more transparent and thorough your package, the faster a private lender can determine if your Indian River County deal aligns with their underwriting approach.
When another financing option may be a better fit
Not every real estate investment in Vero Beach will be suited to a fix and flip loan. Long-term rental acquisitions, owner-occupied homes, properties with incomplete documentation, or new investors without relevant experience may be better served with alternative private loan programs or conventional bank options, depending on need and risk tolerance. For projects with heavy structural work, unusual zoning, or lengthy timelines—especially common in parts of Port St. Lucie or properties near the river—consider options that provide longer terms, lower leverage, or greater flexibility. Private lending is most valuable when it closely fits the business purpose and borrower’s execution readiness.
Real Estate Investor Financing FAQs
Are Vero Beach fix and flip loans available for investors without perfect credit?
Yes, AFI Private Lenders does not rely heavily on traditional credit scores for qualifying fix and flip loans. The strength of the property and project plan are emphasized.
Can I use a Vero Beach investment property loan for a rental conversion instead of resale?
Yes, if the exit strategy is clear and supported by the local market, a fix and flip loan can lead to rental conversion. Share your plan with the lender during the application process.
What documents are needed for an initial fix and flip loan review in Indian River County?
A purchase agreement, detailed renovation budget, property information, comparables, and a summary of your experience are typically required for initial review.
How does AFI handle renovation budget and construction draws?
For qualifying projects, AFI aims to keep construction draw requests straightforward, subject to inspections and the underlying loan agreement.
Can first-time flippers get approved for Vero Beach fix and flip loans?
Each application is judged on the overall project quality, documentation, leverage, and the investor's relevant background. Approval is not guaranteed for first-time builders.
Does AFI provide financing outside of Vero Beach?
Yes, AFI Private Lenders considers investment property financing throughout Florida, including Sebastian, Fellsmere, and other Treasure Coast cities.
Have a Vero Beach investment property to finance?
Send the property address, requested loan amount, property type and investment plan for an initial review.