A practical guide for Sanford and Seminole County real estate investors on qualifying for fix & flip loans. Learn how AFI Private Lenders evaluates suburban and infill projects.
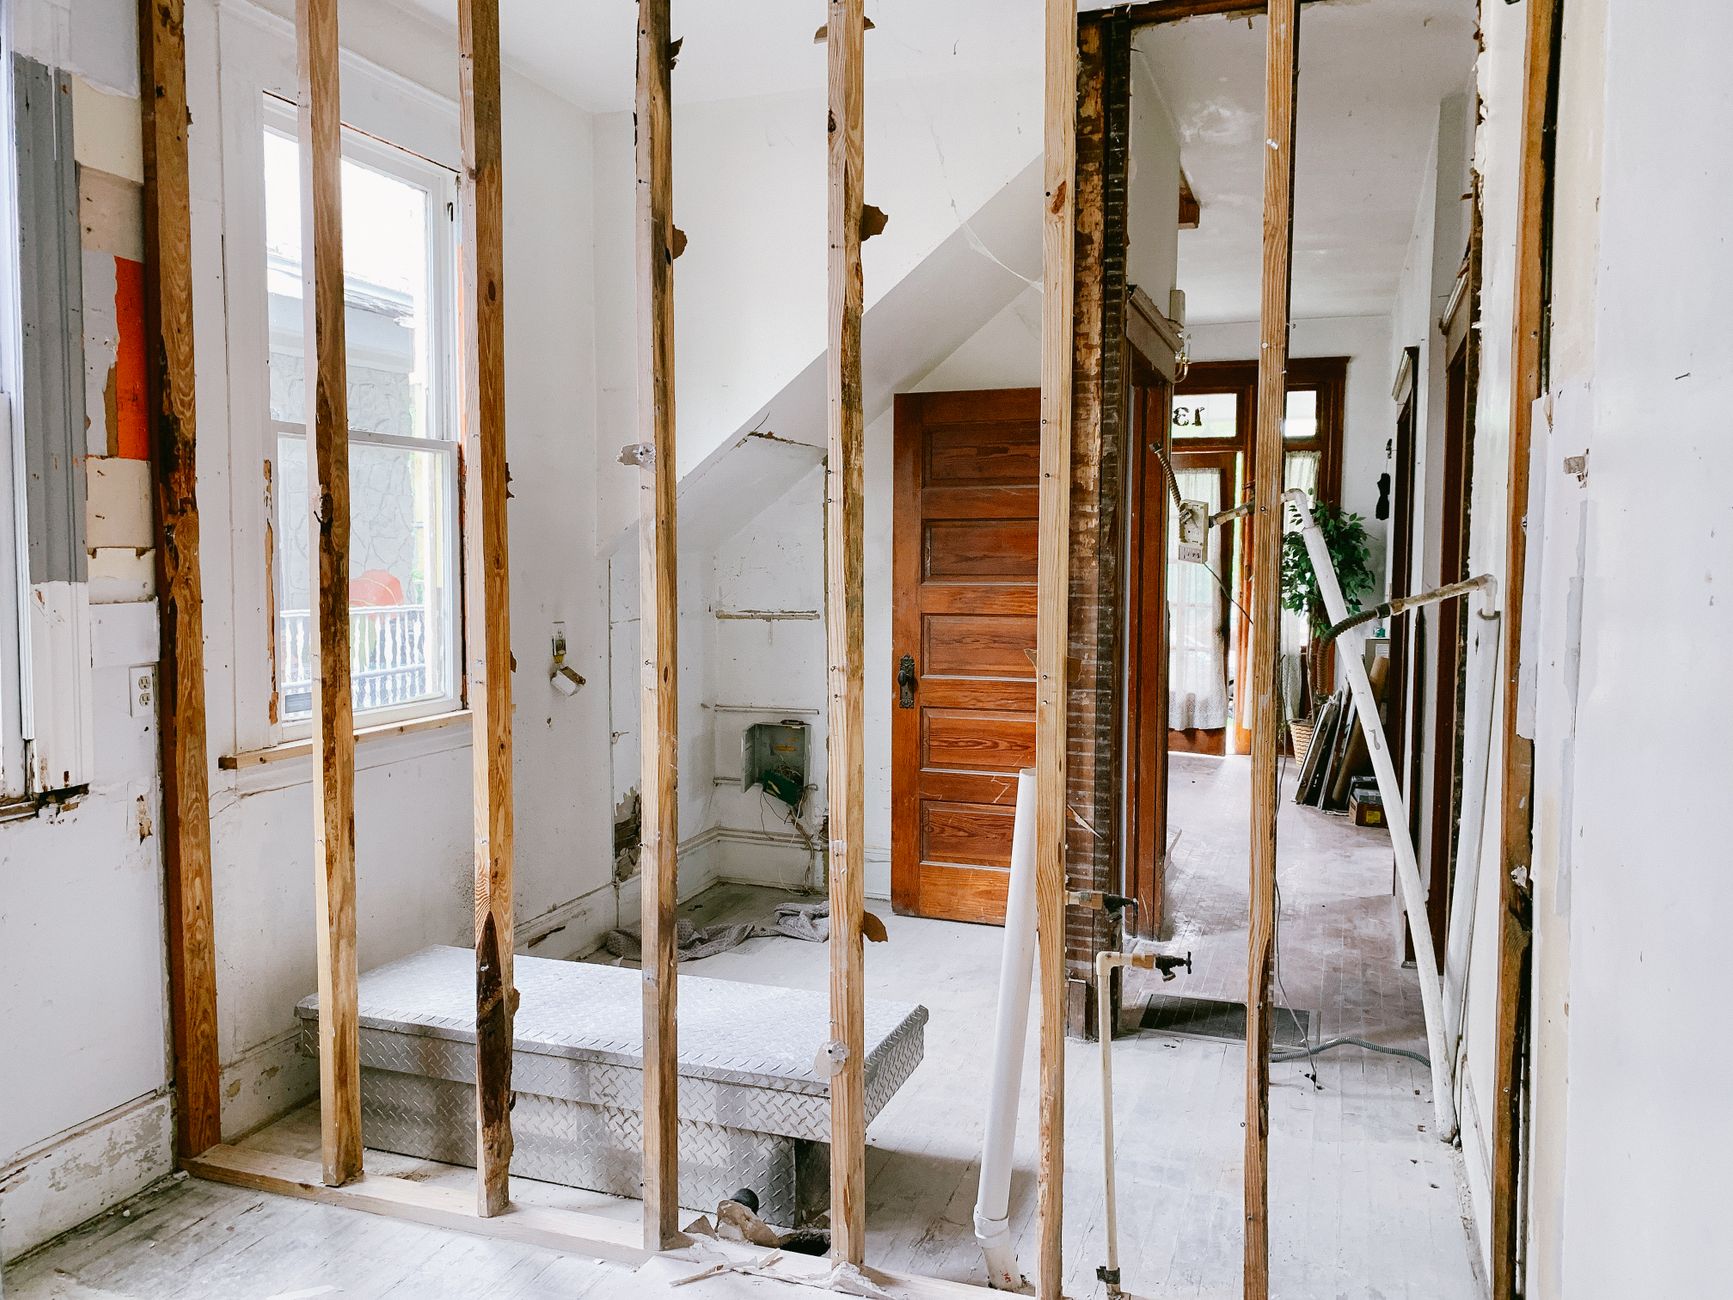
For Sanford real estate investors, acquiring and renovating homes is more than a business—it's a way to shape growing neighborhoods from Lake Mary to Longwood. But even experienced investors find that the right financing can make or break a project’s timeline and returns.
This guide explores how AFI Private Lenders approaches Sanford fix and flip loans, with a focus on suburban and infill opportunities throughout Seminole County. Discover what matters most in local loan evaluations and how to prepare your investment property project for review.
How Sanford Fix and Flip Loans Are Evaluated
Fix and flip opportunities in Sanford and surrounding Seminole County neighborhoods are often evaluated quite differently from traditional residential loans. AFI Private Lenders considers the unique investment characteristics of each property and project, emphasizing local supply-and-demand patterns and the property’s specific potential. While Sanford’s housing inventory includes everything from older Craftsman cottages near downtown to mid-century and newer homes in Lake Mary and Winter Springs, the process for qualifying fix and flip loans Sanford Florida investors pursue always begins with a holistic review of property, project scope, and investment rationale.
Purchase Price, Current Condition & Renovation Scope
Sanford’s mix of historic homes, post-war properties, and newer infill construction creates different starting points for investors. AFI evaluates each application in the context of purchase price, current condition, and the planned renovation scope, especially in transitional neighborhoods and suburban pockets near Longwood or Oviedo. Investors should be prepared to present detailed information about the acquisition cost, required repairs, anticipated upgrades, and how improvements will enhance property value and marketability after completion.
Why the Property and Project Matter More Than Traditional Credit Scoring
Unlike many lenders, AFI Private Lenders does not rely heavily on traditional credit scoring criteria for qualifying Sanford investment property loans. Instead, primary focus is placed on the property and the project itself—location, planned improvements, investor experience (if any), deal structure, and exit strategy. This often benefits experienced buyers and builders targeting Seminole County infill and value-add projects, making loan decisions more about the investment’s fundamentals than a single credit number.
Rehab Budget, Contractor Planning & Construction Draws
Clear, realistic budgets and well-organized contractor planning help fix and flip projects succeed in markets from Altamonte Springs to Sanford. AFI aims to keep construction draw requests straightforward for qualifying projects: upon submission, they are reviewed based on progress inspections and requirements set forth in the loan documents. Investors should build a comprehensive rehab budget and select contractors with a track record in comparable suburban projects, factoring in realistic costs for permits, materials, and potential delays common in Seminole County renovations.
Borrower Liquidity, Contingency, and Carrying Costs
Liquidity is a critical factor—especially when working in neighborhoods where unforeseen issues may arise during construction. For Sanford fix and flip projects, AFI Private Lenders looks for sufficient reserves to handle carrying costs, contingency overruns, and the ability to maintain progress through to resale, rental, or refinance. Investors should demonstrate their ability to manage monthly holding costs, including taxes, insurance, and utilities through the project timeline. Projects in Lake Mary, Oviedo, and other nearby cities may involve unique carrying cost considerations depending on property type and anticipated market absorption.
Exit Strategy: Resale, Refinance, or Rental Conversion
Successful fix and flip lending in Sanford depends on a clear exit strategy. Whether the goal is to resell, refinance, or convert to a rental, AFI evaluates the plausibility and logic of your plan based on current marketing conditions in Seminole County. Strong justification for your exit—supported by market comps, anticipated timelines, and rental or sales demand—strengthens your proposal, regardless of whether your investment is in suburban Altamonte Springs or a revitalizing Sanford infill corridor.
What to Send AFI for an Initial Review
When preparing to submit a Sanford investment property loan request, organization is key. AFI Private Lenders recommends providing:
- Purchase contract (or letter of intent if not yet in contract)
- Detailed renovation scope and budget
- Analysis of comparable sales or rents
- Project timeline and contractor info
- Outline of your exit strategy
- Summary of your relevant experience
- Basic information about your liquidity and reserves
When Another Financing Option Might Fit Better
Not every Sanford or Seminole County project will be a perfect match for fix and flip financing. If the renovation scope is extremely minor (a light cosmetic update), or, conversely, if the project involves heavy ground-up construction or lengthy entitlement, another loan structure may be a better alternative. Likewise, first-time investors may find entry requirements stricter than those for seasoned professionals. For long-term holds, rental property loans might suit investor goals better than fix and flip loans. Consider discussing your project’s unique needs with AFI to identify the optimal financial strategy for your next Sanford investment.
Real Estate Investor Financing FAQs
What types of Sanford properties are eligible for fix and flip loans?
Typically, single-family homes, townhomes, or small multifamily properties intended for renovation and eventual resale or rental in Sanford and nearby Seminole County communities can be considered. All must meet AFI’s underwriting requirements.
Does my credit score affect my chances of getting a Sanford fix and flip loan?
AFI Private Lenders does not rely heavily on traditional credit scoring when evaluating qualifying fix and flip loans. The project itself, property, and exit strategy are more heavily weighted.
How important is my renovation scope and budget for approval?
A clear, realistic renovation scope and budget are crucial, as AFI evaluates how improvements will impact property value and marketability. Detailed planning demonstrates your project’s viability.
Can first-time investors get fix and flip loans in Sanford?
While all projects are considered, AFI’s process may favor investors with experience, especially with complex or value-add property types. Approval is never guaranteed for first-time builders.
What documents should I prepare for a Sanford investment property loan review?
Prepare a purchase contract, detailed renovation scope and budget, comps, contractor info, project timeline, your exit strategy, summary of experience, and proof of liquidity.
What if my project is in Lake Mary or Altamonte Springs, not Sanford?
AFI Private Lenders serves all of Seminole County, including Lake Mary, Altamonte Springs, and other communities. The evaluation process remains consistent across the area.
What if my project doesn’t fit traditional fix and flip loan guidelines?
Some projects, such as minor cosmetic flips or major ground-up builds, may benefit from alternative financing structures. AFI can help discuss your best options for Seminole County investments.
Have a Sanford investment property to finance?
Send the property address, requested loan amount, property type and investment plan for an initial review.