Explore how Pensacola fix and flip loans are evaluated—including project budget, property condition, and carrying costs—for successful real estate investment financing in Northwest Florida.
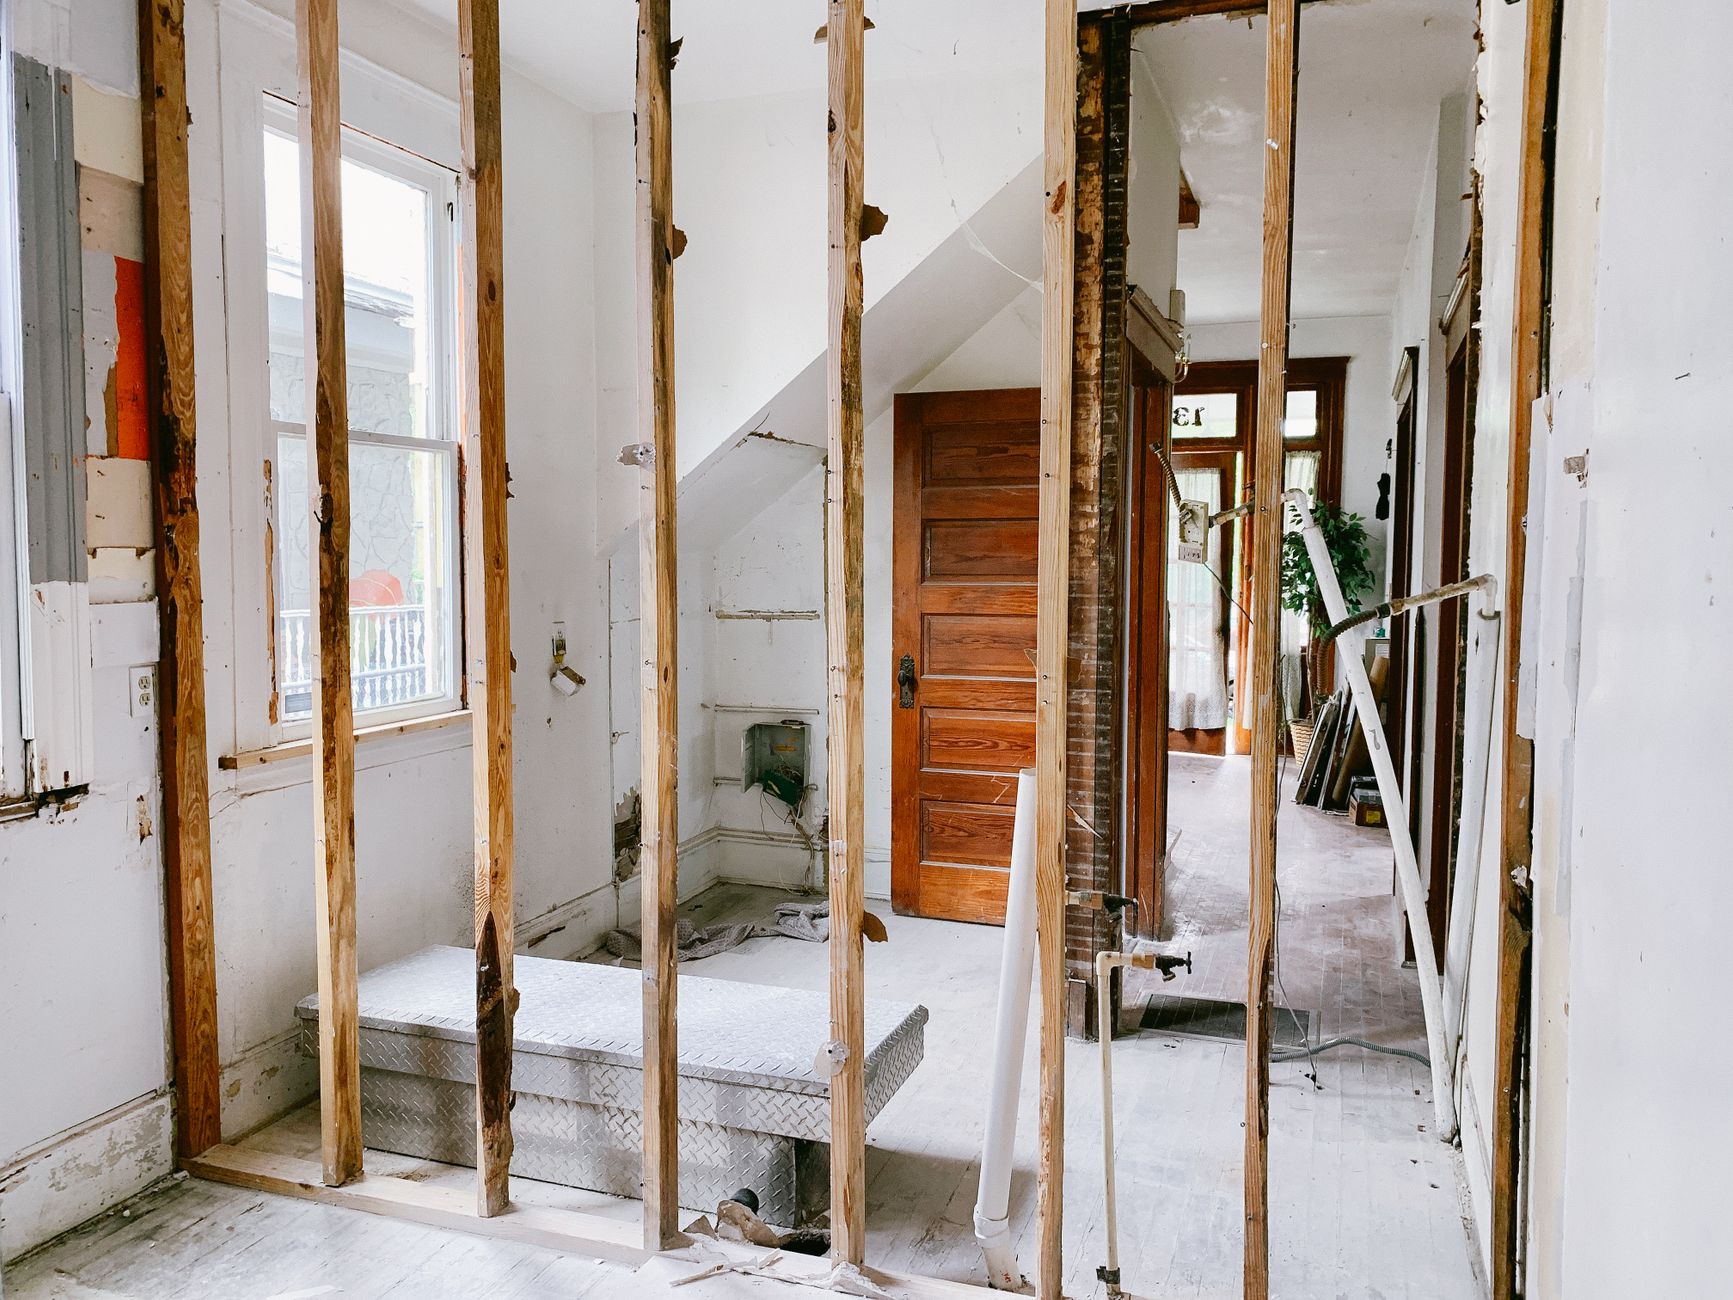
Fix and flip projects in Pensacola and surrounding Escambia County communities have their own financing needs. Investors and renovators must consider more than just purchase price—property condition, project scope, rehab budget, and local market nuances all play a major role in determining both project feasibility and financing structure.
This guide dives into how Pensacola fix and flip loans are evaluated, what details matter most to private lenders like AFI, and what local investors in Northwest Florida should prepare before pursuing business-purpose real estate funding for their next opportunity.
How Pensacola Fix and Flip Loans Are Evaluated
Unlike conventional financing, Pensacola fix and flip loans from private lenders like AFI focus on several investment-specific factors rather than relying primarily on a borrower's credit score. AFI reviews the property type, renovation plan, project leverage, and the investor’s business strategy. Whether pursuing opportunities in Pensacola itself, Gulf Breeze, Pace, Milton, or Pensacola Beach, the key is aligning your project with local market expectations and the unique requirements of Northwest Florida’s housing stock.
Purchase Price, Current Condition, and Renovation Scope
One of the first considerations for a fix and flip financing request is the purchase price compared with the property’s current condition. Older homes in historic Pensacola neighborhoods, mid-century properties in Pace, or condos near Pensacola Beach each present different renovation challenges and return-on-investment profiles. Your renovation's scope—cosmetic updates, full system overhauls, or structural repairs—directly affects the project’s risk and budget needs. Lenders will weigh how realistic the post-repair value is for the specific property and market segment.
Why the Property and Project Can Matter More Than Traditional Credit Scoring
With fix and flip loans Pensacola Florida investors should note that lenders like AFI do not rely heavily on traditional credit scoring. Instead, underwriting centers on the merits of the investment property, the business plan, leverage requested, and the borrower’s experience and strategy. While credit often plays some role, a viable project with sound numbers in Pensacola or Milton may still secure financing if the project fundamentals are strong and well-documented.
Rehab Budget, Contractor Planning, and Construction Draws
Your renovation budget needs to be detailed, realistic, and matched to local labor and material costs in the Pensacola region. Private lenders review line-item rehab plans, contractor agreements, and verify that licensed professionals are engaged where required. AFI aims to keep construction draw requests straightforward for qualifying projects, but each draw is subject to loan documents, inspections, and underwriting benchmarks. Overestimating resale value or under-budgeting local construction costs can create hurdles, making a precise budget essential for approval.
Borrower Liquidity, Contingency, and Carrying Costs
Pensacola investment property loans often require that investors show adequate liquidity—not just to start renovations, but also to cover unexpected setbacks, delays, and ongoing carrying costs for taxes, insurance, and utilities. Carrying costs can shift market to market; for example, properties closer to Pensacola Beach may face higher insurance expenses due to storm risks. Lenders will want to see a contingency fund built into your financial plan, especially if the local market shifts during your rehab timeline.
Exit Strategy: Resale, Refinance, or Rental Conversion
Having a clear, market-appropriate exit strategy is essential for any fix and flip project in Pensacola and neighboring Escambia County towns. Whether you plan to resell, refinance, or hold the renovated property as a short-term or long-term rental, your loan submission should include a defined, plausible plan backed by current market insights. For example, a property in Gulf Breeze might appeal to different buyer pools or rental audiences than one in central Pensacola. Lenders like AFI will review your exit plan as a core part of the financing decision.
What to Send AFI for an Initial Review
To start a fix and flip loan application, Pensacola investors should assemble: a full property description, purchase contract, photos showing the current condition, a detailed and local-market-aware budget, a contractor/renovation plan, evidence of liquidity, and your intended exit strategy. AFI also factors in relevant experience, though successful first-time investors may be considered for qualifying projects. Submitting a comprehensive package accelerates underwriting and helps clarify whether the deal aligns with lender guidelines in Escambia County.
When Another Financing Option May Be a Better Fit
Not every property or investor profile is right for private fix and flip funding. Highly distressed properties with unknown costs, projects lacking documented contractor bids, or investors unable to demonstrate liquidity or a workable exit plan might consider other financing structures. For example, longer-term rental conversion opportunities or projects needing more incremental funding could be better served by alternative commercial or bank-originated loans. Discuss your goals with AFI to determine the best structure for your Escambia County investment.
Real Estate Investor Financing FAQs
Do Pensacola fix and flip loans require perfect credit?
No. AFI does not heavily rely on traditional credit scoring for qualifying fix and flip loans; project details and property condition are more important underwriting factors.
Can first-time investors qualify for fix and flip loans in Pensacola?
Possibly. While experience is considered, strong projects with complete budgets, clear exit strategies, and investor readiness are central for underwriting.
What documents are needed to start a loan review with AFI?
Commonly requested items include a purchase contract, property photos, renovation scope, detailed budget, contractor plan, financial statements, and exit strategy.
How are construction draws handled for Pensacola projects?
Draws are processed according to the loan documents, with inspections and underwriting requirements. AFI aims to keep the process practical for qualifying projects.
Are Pensacola fix and flip loans available for properties in nearby cities like Pace or Gulf Breeze?
Yes, AFI considers qualifying business-purpose investment properties throughout Escambia County and adjacent Northwest Florida markets.
Is there a minimum property value or loan amount for fix and flip loans?
Loan qualification depends on property type, project scope, and leverage—not just a minimum value or loan size. Each request is individually underwritten.
Can I use a fix and flip loan to convert a property to a rental after renovation?
Yes, if the exit strategy involves rental conversion, this should be included in your application and business plan to assist lender evaluation.
Have a Pensacola investment property to finance?
Send the property address, requested loan amount, property type and investment plan for an initial review.