Explore how Ocala real estate investors, builders, and property owners can approach new construction loans. Get tips for planning, budgeting, and approvals.
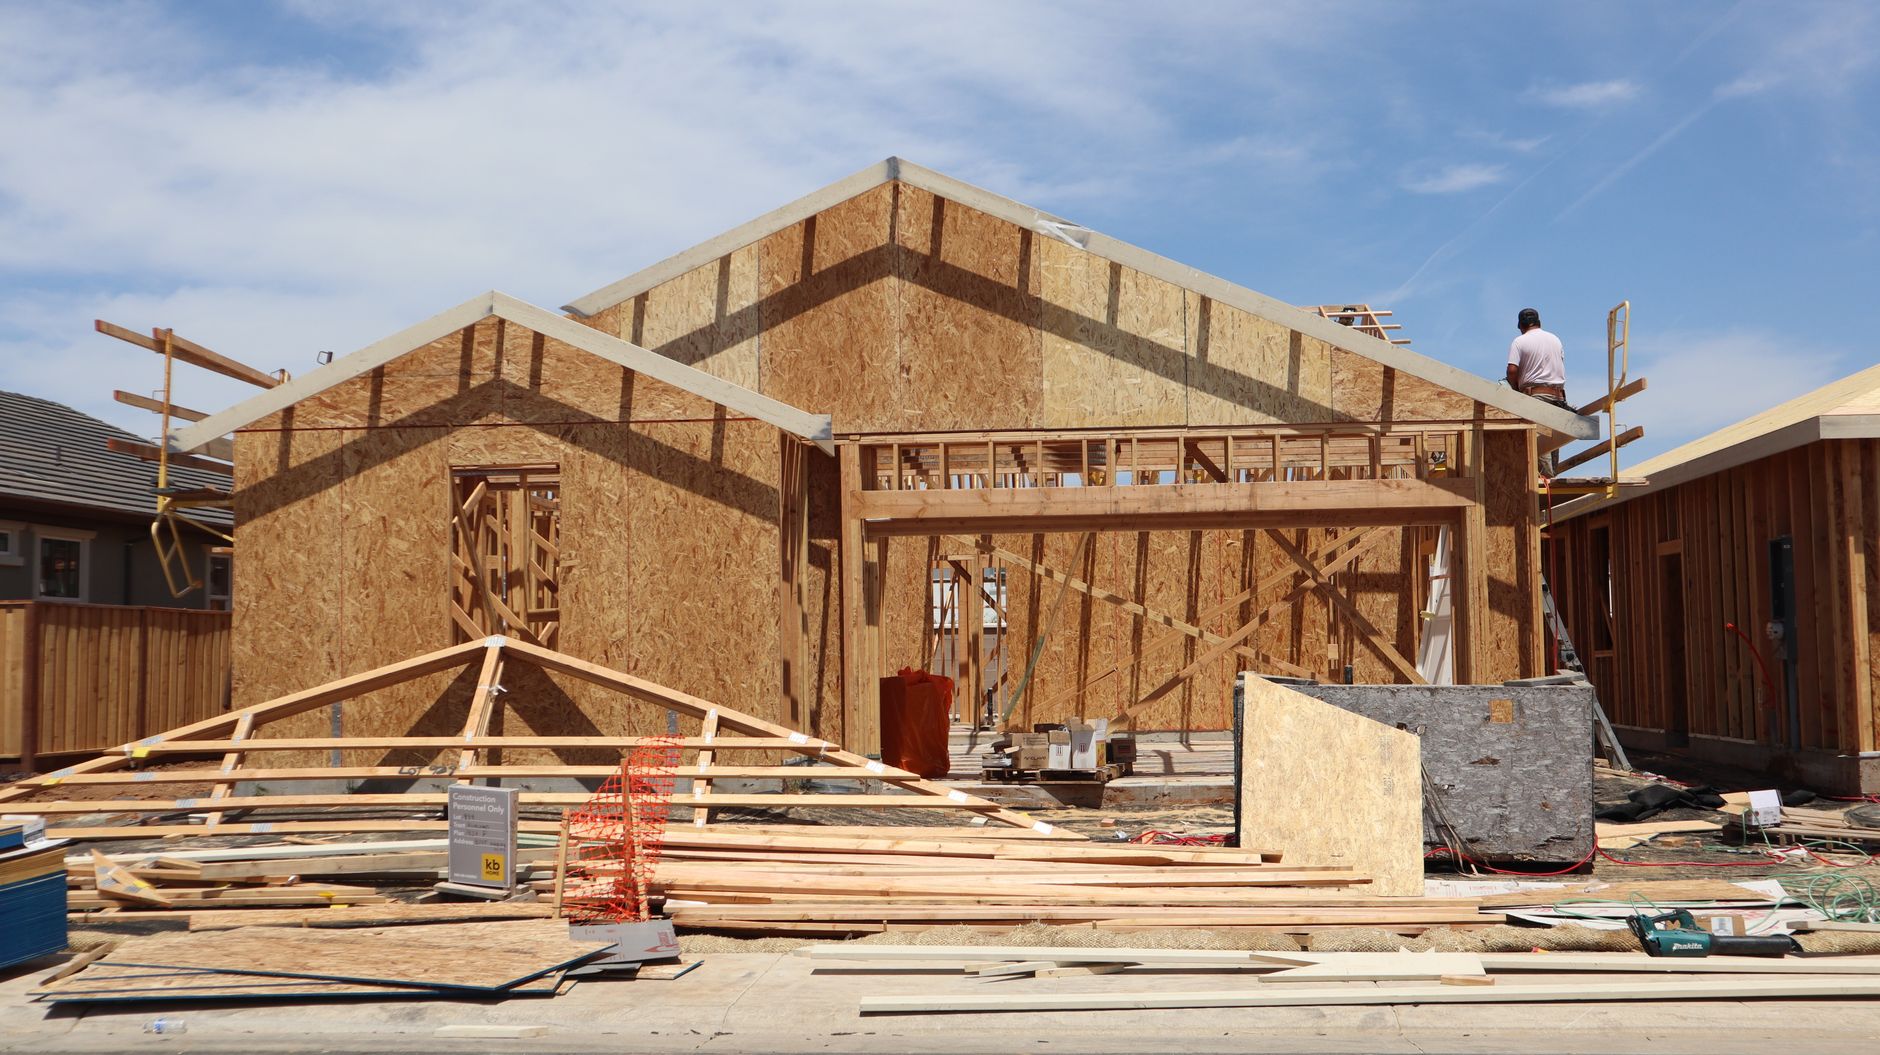
With Ocala’s steady population growth and its role as a regional hub in North Central Florida, real estate investors are increasingly eyeing new construction opportunities. Whether building rental homes, small commercial spaces, or leveraging land-adjacent investments in Marion County, securing the right financing is crucial to investor success.
This guide examines how Ocala new construction loans are evaluated, what makes a project financeable, and strategies for clear budget and payoff planning tailored to residential, land-adjacent, and small commercial properties. Investors from Belleview to Dunnellon will find actionable insights on how to position their new construction deals for review with private lenders like AFI Private Lenders.
What Makes a Ground-Up Construction Request Financeable in Ocala?
For investors seeking Ocala new construction loans, financeability starts with a strong project concept and clear alignment with local market demand. Lenders focus on business-purpose properties—such as spec homes for resale, build-to-rent single-family projects, and small mixed-use or commercial properties—especially in Marion County’s most active corridors.
Key criteria often include a market-supported use for the property, clarity on intended exit (sale, refinance, or rental stabilization), and a proposed budget that aligns with both cost and value. Requesting leverage based on a realistic completed value and demonstrating how your deal provides both the lender and the investor a reasonable margin are foundational to a financeable loan proposal in Ocala.
Land, Plans, Permits, and Project Readiness
Lenders like AFI Private Lenders evaluate a construction loan based on the development readiness of the site. This means investors should have site control—ownership or a contract for the buildable land—along with a development plan that is practical for the property’s zoning and utility access. Having architectural plans drafted and submitted for permit review, or at least in final-preparation stages, strengthens a submission and may speed up lender review.
In areas bordering Silver Springs or Belleview where land parcels are commonly developed adjacent to established subdivisions, clarity on actual access, utility connections, and realistic timeline to permit approval helps mitigate project delays and informs the loan underwriting process. Lenders may also consider unique features such as proximity to highways or growth corridors as part of their risk analysis.
Builder, General Contractor, and Project-Team Considerations
Strong new construction loans in Ocala and surrounding Marion County communities are backed by credible project teams. Whether you’re a first-time builder or a seasoned developer, lenders consider the strength of your builder, contractor, and any key consultants. AFI Private Lenders is open to reviewing qualifying requests from first-time builders, but approval is not guaranteed. Inclusion of a reputable, experienced general contractor and subcontractor roster gives your project more credibility—especially for larger or more complex builds.
Clear communication of contractor credentials, licensing (where required), and relevant local track record (including prior projects in Ocala or Dunnellon) can increase lender confidence. If you’re working with a project manager or design consultant, provide their background as part of your submission.
Budget Detail, Contingency, and Borrower Liquidity
A successful new construction loan request has a detailed, realistic budget. Lenders are interested not just in hard construction costs, but in soft costs such as professional fees, permit expenses, inspections, and contingency reserves. In Marion County, cost overruns can happen due to site conditions, weather delays, or changing material prices—so building in a contingency line (typically 5-15% of total costs) is wise.
Lenders will assess the borrower’s liquidity. Having accessible funds to cover pre-construction expenses and unexpected costs indicates ability to withstand common setbacks. Including proof of reserves, clear cost disclosures, and honest cost projections can reduce delays and avoid surprises at closing.
How Construction Draws Work After Closing
Ocala investment property loans for new construction are typically disbursed in draws after closing, aligned with project milestones. AFI Private Lenders strives to keep draw requests straightforward and practical, subject to loan documents, project inspections, and underwriting standards. Most draws are tied to verified completion of specific stages: site clearing, foundation, framing, dry-in, and finishes. All draw requests require documentation, inspections, and sometimes lien releases from contractors.
Clear draw scheduling and proactive communication between the borrower, contractor, and lender can help keep projects in Belleview, Dunnellon, or central Ocala on track. Delayed inspections or incomplete paperwork are common causes of funding slowdowns, so advance planning is essential.
Schedule Risk, Cost Overruns, and Change Orders
Every new construction project in Marion County must allow for the possibility of schedule slips and cost increases. Local weather conditions, supply chain delays, or required design changes may affect both timeline and budget. Lenders expect smart risk management, including transparency on what changes could impact the bottom line.
If you anticipate major changes, promptly document and communicate them to your lender, ideally before executing change orders with your contractor. Failure to stay ahead of these issues can threaten funding continuity and ultimately the project’s profitability. Smart investors in the Ocala market prepare backup plans to ensure they can handle delays or additional expenses without risking loan default.
Sale, Refinance, and Rental-Stabilization Exits
Lenders want to understand your exit plan—whether it’s selling finished homes, refinancing into long-term rental loans, or stabilizing retail or office space. In Ocala and its commuter communities, market demand for single-family rentals and small commercial space remains solid, but execution is key. Clear plans for marketing, leasing, or refinance are essential for a successful payoff.
Discuss any relationships you may have with local realtors, property managers, or financial partners. Lenders often look for documented strategies for a timely sale, lease-up, or refinance. If another structure—such as a long-term rental loan—may better align with your goals, a lender can help you assess that trade-off.
A Construction-Loan Submission Checklist for Ocala Investors
To improve your chances of approval and a smooth closing in Ocala or broader Marion County, prepare a complete submission that includes:
- Site information and proof of control (deed, contract, survey)
- Detailed construction budget with contingency
- Architectural plans and scope of work
- Permit status and projected timeline
- General contractor information and credentials
- Borrower financials and proof of liquidity
- Proposed exit strategy (sale, rental, or refinance)
- Contractor agreements and, if available, lien waivers
Careful preparation up front can streamline communication with your Ocala private lenders and help avoid common pitfalls during the draw process.
Real Estate Investor Financing FAQs
Can first-time builders in Ocala get new construction loans?
AFI Private Lenders is open to reviewing requests from first-time builders. Approval depends on the project’s strength, the team, budget, and exit plan.
Do I need permit approvals in place before applying?
You do not need permits in hand, but having your plans submitted or near-final aids your loan review and demonstrates project readiness.
What information do Ocala private lenders require for new construction loans?
Expect to provide land documentation, plans, a detailed budget, contractor info, borrower finances, project timeline, and your intended exit strategy.
How are Ocala construction draws typically managed?
Funds are disbursed after each construction milestone is inspected and verified. Documentation and clear scheduling help keep draws timely and predictable.
What if my budget changes during construction?
Notify your lender immediately about cost overruns or change orders. Lenders may require revised budgets and proof you can cover added costs.
Is heavy credit scoring required for loan approval?
For fix-and-flip loans, traditional credit scoring is not relied on heavily, but overall project strength and borrower experience still matter.
Are new construction loans available for properties in Belleview or Dunnellon?
Yes, qualifying business-purpose projects in Belleview, Dunnellon, Silver Springs, or across Marion County can be considered for new construction loans.
Have a Ocala investment property to finance?
Send the property address, requested loan amount, property type and investment plan for an initial review.