Explore how Jupiter investors, builders, and landlords can approach new construction loan requests—from land and permits to draw schedules and exit planning.
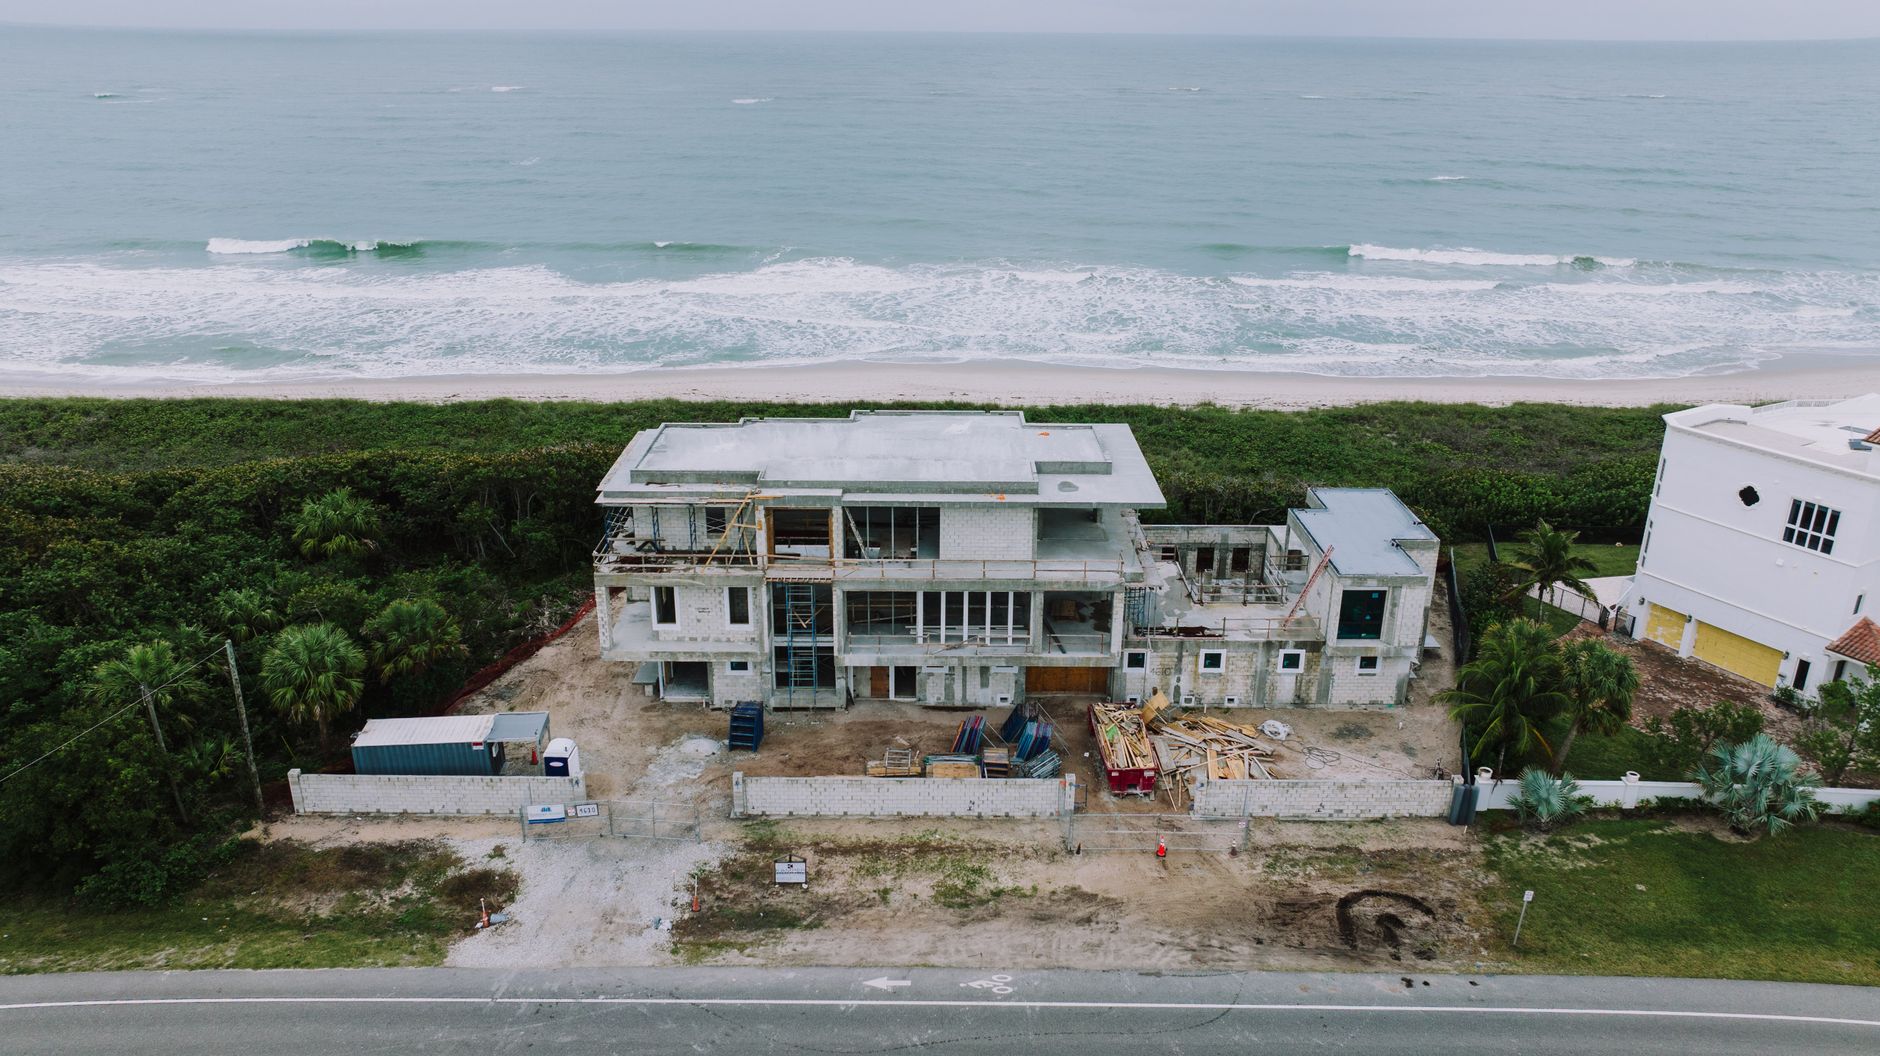
For real estate investors targeting new builds in Jupiter, Florida, getting a project financed means more than finding available capital. Local market dynamics, coastal protections, and the detailed scrutiny of suburban developments shape how private lenders evaluate Jupiter new construction loans. Investors need to demonstrate more than land ownership—they must document planning, budget, team competency, and a clear path to a profitable exit.
Whether you’re planning ground-up construction in Jupiter, Palm Beach Gardens, or nearby Tequesta, understanding the private lending perspective is crucial. This guide unpacks the major factors influencing business-purpose new construction loans in Jupiter, highlighting investor-specific underwriting, project documentation essentials, and risk planning unique to this South Florida market.
What Makes a Ground-Up Construction Request Financeable in Jupiter?
For Jupiter new construction loans, lenders weigh whether a project is both feasible and financeable under local market conditions. Beyond land value, investor proposals are measured on several criteria: site readiness, outlined plans, builder experience, local permitting progress, and a realistic budget. Lenders look for evidence that coastal or suburban conditions—like wind zone requirements, stormwater plans, and market fit—have been acknowledged. For business-purpose borrowers, the project must directly benefit an eligible investment property, contributing to the growth, rental, or resale potential in Jupiter or surrounding Palm Beach County communities.
Land, Plans, Permits, and Project Readiness
Lenders serving Jupiter and neighboring areas understand that ground-up builds require substantial front-end preparation. The strongest submissions document land control (owned or under contract), civil plans, architectural drawings, and preliminary permitting steps. Without these, construction readiness remains questionable—especially in regulated coastal markets. While complete permits aren’t always necessary to begin loan underwriting, credible evidence of progress reassures private lenders, particularly for builds in Palm Beach Gardens, Juno Beach, or flood-prone sections near the Loxahatchee River. Keep records organized and highlight any unique environmental or jurisdictional hurdles your project addresses up front.
Builder, General Contractor, and Project-Team Considerations
The selection and documentation of your project team directly affect a lender’s comfort level. AFI Private Lenders is open to reviewing applications from first-time builders, but track record, contractor licensing, insurance, and local experience remain important. Navigating Jupiter’s permitting processes or complying with Palm Beach County construction codes requires capable oversight. Detailed bios, resumes, and references increase lender confidence—especially if your builder or general contractor has successfully delivered projects in surrounding towns like Tequesta or Hobe Sound. Lenders want to see clear roles for architects, engineers, and site supervisors to lower contractor risk and signal professional management.
Budget Detail, Contingency, and Borrower Liquidity
Comprehensive budgets are a critical gatekeeper for Jupiter investment property loans. Incomplete cost breakdowns or vague “soft costs” tend to stall the process. Lenders typically scrutinize line-item details, ensuring they reflect actual local build costs, contractor bids, and supplier quotes. Budget contingencies—funds set aside for unknowns—are essential in a market known for variable weather and seasonal material spikes. Documenting your available liquidity underscores your ability to cover shortfalls, absorb cost overruns, or bridge construction draws if needed. Private lenders respond positively to borrowers who are transparent about their capital stack, including reserves for insurance, taxes, and utilities associated with Jupiter new construction loans.
How Construction Draws Work After Closing
After closing, construction proceeds are typically advanced in stages—known as draws—based on project milestones verified by inspections. AFI Private Lenders aims to keep draw requests practical and straightforward, subject to the loan documents and inspections required. In Jupiter, lenders will review completed work before releasing funds, ensuring that each phase—foundation, framing, roofing, systems, and finishes—meets expectations and budget allocations. Clear documentation with inspection reports, lien waivers, and contractor invoices accelerates draw approvals and minimizes disputes. Timely draw management is crucial to keeping investor projects on track, especially when working across multiple Palm Beach County sites.
Schedule Risk, Cost Overruns, and Change Orders
Construction in Jupiter and Palm Beach County faces unique timeline risks: weather delays, material shortages, or even coastal permitting slowdowns. Lenders want to see owner awareness and contingency planning for such events. Formal change order protocols—where work scope and budget changes are documented—help prevent disputes, clarify accountability, and reassure lenders. AFI and other Jupiter private lenders may request revised budgets or updated schedules if scope changes significantly. Borrowers who openly communicate project adjustments, regularly update their financial position, and quickly address cost overruns build long-term credibility.
Sale, Refinance, and Rental-Stabilization Exit Strategies
New construction loans in Jupiter Florida always require a clearly mapped exit strategy—how the loan will be paid off after completion. Lenders need to see documentation supporting your exit, whether you plan to sell the property, refinance into long-term debt, or stabilize it as a rental. For coastal or waterfront homes, local comps and realistic sale projections strengthen your case. If you plan to refinance, broker conversations, pre-qualification letters, or interest from rental lenders are persuasive. Rental stabilization in rapidly growing neighborhoods like Abacoa or Tequesta should detail pre-leasing activity and anticipated cap rates. The more data-driven and detailed your exit plan, the more likely your financing request is to move forward smoothly.
A Construction-Loan Submission Checklist for Jupiter Investors
- Land Documentation: Proof of ownership or control (contract, deed, or purchase agreement)
- Plans and Permits: Architectural drawings and progress on permits
- Budget: Detailed, line-item construction budget with contingency funds
- Project Team: Bios, licenses, insurance, and references for general contractor and key team members
- Insurance: Evidence of builder’s risk policy or commitment to secure same
- Schedule: Construction timeline from groundbreaking through completion
- Draw Schedule: Outline of anticipated draw requests by milestone
- Exit Strategy: Supporting documentation for sale, refinance, or rental plan
- Liquidity Evidence: Proof of cash reserves or investor contributions
Providing a thorough, transparent package tailored to both the deal and the nuances of the Jupiter market significantly improves the odds of securing private construction loan financing.
Real Estate Investor Financing FAQs
Who qualifies for Jupiter new construction loans with AFI Private Lenders?
AFI considers business-purpose real estate investors, builders, and landlords with qualifying projects in Jupiter and Palm Beach County. Approval depends on deal strength, team, budget, plans, permits, liquidity, and a clear exit strategy.
Do you finance first-time builders in Jupiter?
AFI is open to reviewing requests from first-time builders, but approval depends on the overall project strength, budget, team experience, and supporting documentation.
How are construction draws handled during the build in Jupiter?
Draws are typically released at defined project milestones after inspections and documentation checks. AFI aims to keep draw requests straightforward per the loan agreement.
What documentation is needed for a Jupiter new construction loan?
Expect to provide land control evidence, plans, permits in progress, a detailed construction budget, team bios, insurance, a schedule, exit plan, and proof of liquidity.
Can coastal or waterfront projects in Jupiter get private financing?
Yes, but waterfront or flood-prone sites may require additional disclosures and insurance coverage. Document how your project addresses zoning, insurance, and environmental requirements.
Is traditional credit scoring a major factor in qualifying?
Traditional credit scoring is not heavily relied upon for qualifying Jupiter fix-and-flip loans, but private lenders do review the financial background and overall borrower profile.
Are investment property loans available for projects in Palm Beach Gardens or Tequesta?
Yes, AFI Private Lenders considers investment property construction loan submissions throughout Jupiter and nearby Palm Beach County communities like Palm Beach Gardens and Tequesta.
Have a Jupiter investment property to finance?
Send the property address, requested loan amount, property type and investment plan for an initial review.